

Multi-asset investment views: Staying Alive
KEY POINTS
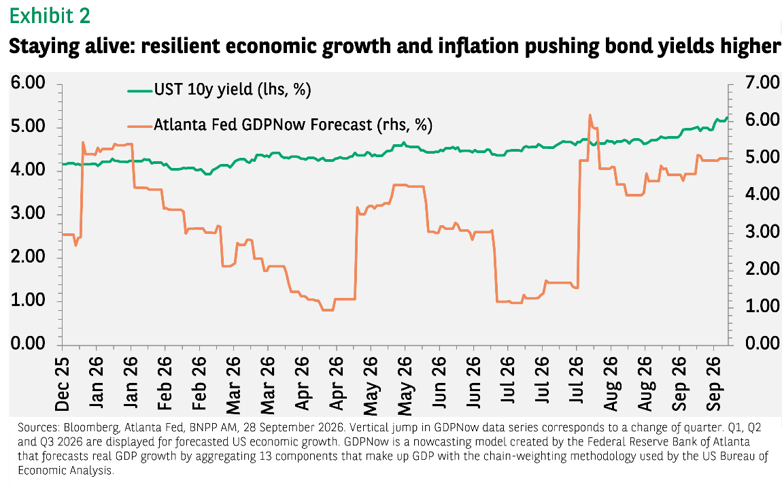
The macroeconomic backdrop remains robust, but so does the balance of risks. There has been no material deterioration in the global growth outlook: US activity remains resilient, Europe has enjoyed a modest improvement and economic indicators point to a broader manufacturing recovery beyond artificial intelligence.
Energy remains the greatest risk, lifting near-term inflation and monetary policy expectations. So far, second-round inflationary effects remain limited, with little evidence of sustained wage increases, suggesting sticky but temporary inflation rather than a higher regime.
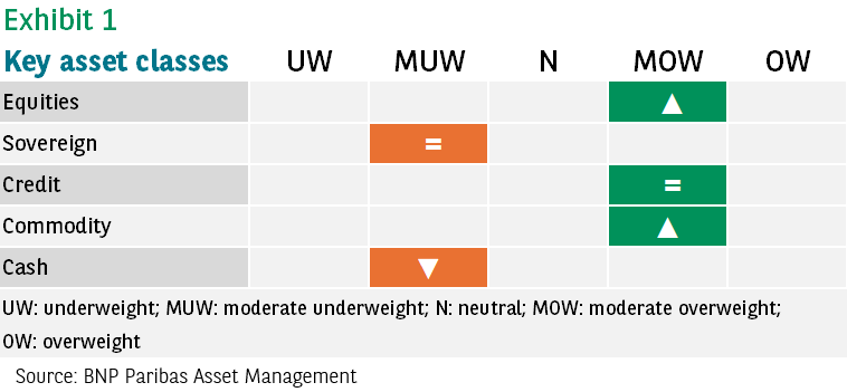
This combination argues for retaining risk exposure, with selectivity and diversification. Resilient activity and earnings continue to support equities and credit assets, while higher energy prices, restrictive central banks, fiscal deficits and sovereign issuance remain headwinds for long-duration government bonds.
Within equities, US earnings and the artificial intelligence investment cycle remain supportive; Japan continues to benefit from growth; fiscal support and corporate-governance improvement; and emerging markets combine attractive relative valuations with improving earnings breadth. Europe has improved, but energy, political and rate risks temper the case for a broader overweight. Our preference would therefore be for a broad equity regional allocation, mainly exposed to US and emerging market stocks, which benefit from sectorial themes such as technology and AI, while in Europe and Japan, we prefer bank stocks.
In fixed income, we favour credit over duration risk, but we are increasingly concerned by the lack of cushion offered by investment-grade bonds. The repricing of policy expectations and attractive short-term yields offer some reasons for optimism, but we still see an unfavourable risk-reward balance in long-duration government bonds and investment-grade credit.
By contrast, shorter-duration, higher-quality, high yield and hard-currency emerging market debt offers attractive potential income while relying less on a fall in long-term yields.
Diversification and dispersion
Commodities remain an important diversifier in the current regime. Energy offers both potential for returns and protection against geopolitical and physical supply risks, while precious metals continue to benefit from structural central bank demand. Industrial metals remain supported by supply constraints, particularly in copper, although a crowded market argues for tactical discipline. With many investors already holding oil positions, we prefer adding when we see price corrections rather than chasing strength.
We also remain constructive on the US dollar, where our exposure remains unhedged and provide additional diversification. At the same time, less volatile equity markets make short-term portfolio protection strategies against sudden drops relatively attractive.
Meanwhile, low correlation between movements in parts of the equity market and wide gaps in performance of different stocks continue to favour relative-value strategies and therefore active management.


Disclaimer
This document is for informational purposes only and does not constitute investment research or financial analysis relating to transactions in financial instruments as per MIF Directive (2014/65/EU), nor does it constitute on the part of BNP PARIBAS ASSET MANAGEMENT Europe or its affiliated companies an offer to buy or sell any investments, products or services, and should not be considered as solicitation or investment, legal or tax advice, a recommendation for an investment strategy or a personalized recommendation to buy or sell securities.
Due to its simplification, this document is partial and opinions, estimates and forecasts herein are subjective and subject to change without notice. There is no guarantee forecasts made will come to pass. Data, figures, declarations, analysis, predictions and other information in this document is provided based on our state of knowledge at the time of creation of this document. Whilst every care is taken, no representation or warranty (including liability towards third parties), express or implied, is made as to the accuracy, reliability or completeness of the information contained herein. Reliance upon information in this material is at the sole discretion of the recipient. This material does not contain sufficient information to support an investment decision.
Issued in the UK by AXA Investment Managers UK Limited, which is authorised and regulated by the Financial Conduct Authority in the UK. Registered in England and Wales, No: 01431068. Registered Office: 22 Bishopsgate, London, EC2N 4BQ.
AXA IM and BNPP AM are progressively merging and streamlining our legal entities to create a unified structure
AXA Investment Managers joined BNP Paribas Group in July 2025. Following the merger of AXA Investment Managers Paris and BNP PARIBAS ASSET MANAGEMENT Europe and their respective holding companies on December 31, 2025, the combined company now operates under the BNP PARIBAS ASSET MANAGEMENT Europe name.