
Multi Asset investment views: “Will of the people”
KEY POINTS
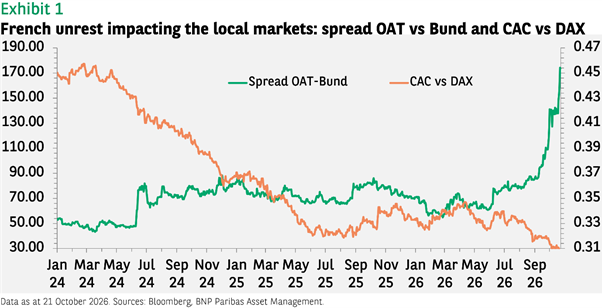
Politics has returned to the forefront of market attention. Social unrest and fiscal uncertainty in France have together pushed sovereign borrowing costs higher and weighed on domestic equities, particularly banks, with some spillover into European credit and neighbouring bond markets.
The CAC 40 has underperformed but represents less than 2% of global equity market capitalisation. Brazil’s presidential election has prompted some moves in local assets, but the main drivers are elsewhere, while the approaching US midterm elections raise questions about policy direction, but are unlikely to change the course of action, notably in the Middle East.
Yet political events do not have a uniform or predictable market effect; historical midterm patterns alone offer little reason to reposition portfolios. The S&P 500 returned an average of 6.6% in the fourth quarter of US midterm election years, and since 1950, has been up 84% of the time.1
The more relevant question is whether political developments alter fiscal credibility, financing conditions or corporate fundamentals. For now, we see reasons for vigilance rather than a broad reduction in risk.
- Source: BNP Paribas Asset Management, October 2026
Growth remains resilient, but momentum may moderate
The global economy has remained more resilient than many expected. Manufacturing activity has recovered over recent months and services remain supportive, although the purchasing managers’ index cycle appears to be maturing.
Our economists are somewhat more cautious than consensus, anticipating a gradual slowdown rather than a recession. China’s growth outlook remains challenged, and we will closely monitor the outcomes of this week’s plenum - the policy meeting of Central Committee of the Chinese Communist Party (CCP).
Inflation is proving sticky, notably because of energy, but there is still limited evidence of sustained second-round wage effects. Against this backdrop, market pricing of roughly two-and-a-half policy-rate increases over the next year for both the Federal Reserve, and the European Central Bank looks more hawkish than our economists’ expectation of approximately one increase each.
This combination continues to favour selective exposure to equities and credit. However, the margin for disappointment has narrowed: higher oil prices, tighter financing conditions or weaker earnings could challenge market confidence. Following the increase in equity exposure at the end of September, we are comfortable maintaining the current risk budget rather than adding to it.
Asset allocation summary
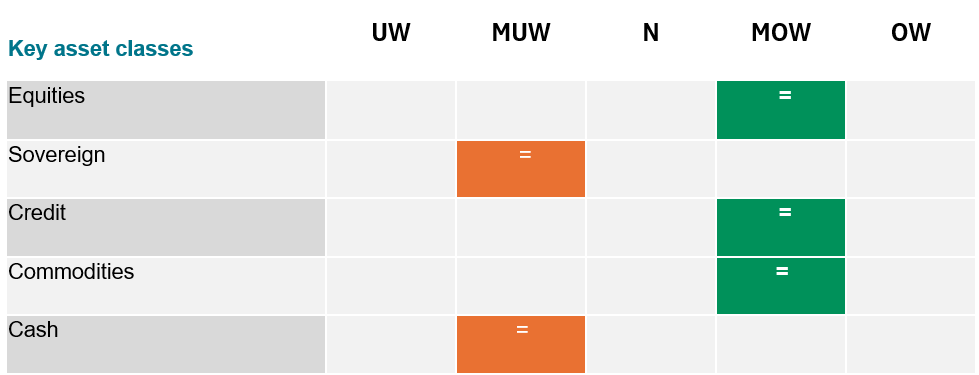
UW: underweight; MUW: moderate underweight; N: neutral; MOW: moderate overweight; OW: overweight, signs = unchanged compared to last month, Source: BNP Paribas Asset Management
Equities: Broaden the sources of return
We retain a moderate overweight in global equities. In the US, earnings growth and artificial intelligence-related investment remain powerful supports but we increasingly favour diversification beyond the largest technology names.
Financials offer attractive valuations, resilient credit fundamentals and solid fee income, notwithstanding recent weakness linked to yield-curve and sovereign-risk concerns. Healthcare also offers comparatively attractive valuations and improving earnings prospects, supported by innovation and technology.
We remain neutral on Europe. Corporate earnings have been relatively resilient, but valuations are less compelling, revisions are losing momentum and persistent inflation could trigger a derating. We continue to favour selected banks, while defence has become more interesting after the sector’s valuation derated and amid improving order prospects.
In France, depressed valuations have prompted a move to neutral at the country level, although political and sovereign-spread risks warrant caution.
We are neutral on Japan. Although it is supported by corporate-governance reforms and fiscal stimulus, we prefer to gain equity exposure through the US and emerging market stocks. In Japan, we favour banks, which benefit from higher rates and strong earnings momentum, alongside selected AI-related companies. Unhedged yen exposure may provide additional diversification.
We also maintain a moderate overweight in emerging markets, supported by exports, earnings and potentially lower US real yields. Recent weakness in Korea appears greater than warranted by semiconductor fundamentals, but index concentration argues against a larger tactical allocation; a broader advance would benefit from improving performance in China and India.
Fixed income: Favour higher income over long duration
We retain moderate underweights in sovereign bonds and investment-grade credit. Government issuance, inflation uncertainty and rising term premia remain challenging, although the repricing of interest-rate expectations has made valuations more interesting.
Deeply negative sentiment could support a short-term recovery, and we are reassessing the size of duration underweights closer to neutral in portfolios with greater flexibility.
We continue to favour shorter-duration, higher-quality high-yield bonds: resilient earnings, stabilising defaults and higher income levels provide a cushion despite recent spread widening. Emerging-market debt also remains attractive, with a growing preference for local-currency exposure where yields are compelling.
Diversification and dispersion
Commodities remain a key portfolio diversifier. Oil markets continue to face supply constraints, shipping disruptions and elevated transport costs; a further spike in prices would pose a material threat to inflation and risk assets.
Precious metals benefit from central-bank buying and renewed exchange-traded fund demand, while copper retains supportive longer-term supply fundamentals, albeit with a need for tactical discipline.
We retain a broadly neutral fundamental view on the euro versus the US dollar and see value in maintaining unhedged dollar exposure as a diversifier, while reviewing contrary quantitative hedging signals.
Equity volatility remains relatively subdued even as cross-asset spillovers become more normal. We therefore continue to favour selective, short-dated equity protection, including three- to six-month put options, rather than materially reducing core risk exposures.
Wide differences in stock and sector performance reinforce the value of diversification and active management.


Disclaimer
This document is for informational purposes only and does not constitute investment research or financial analysis relating to transactions in financial instruments as per MIF Directive (2014/65/EU), nor does it constitute on the part of BNP PARIBAS ASSET MANAGEMENT Europe or its affiliated companies an offer to buy or sell any investments, products or services, and should not be considered as solicitation or investment, legal or tax advice, a recommendation for an investment strategy or a personalized recommendation to buy or sell securities.
Due to its simplification, this document is partial and opinions, estimates and forecasts herein are subjective and subject to change without notice. There is no guarantee forecasts made will come to pass. Data, figures, declarations, analysis, predictions and other information in this document is provided based on our state of knowledge at the time of creation of this document. Whilst every care is taken, no representation or warranty (including liability towards third parties), express or implied, is made as to the accuracy, reliability or completeness of the information contained herein. Reliance upon information in this material is at the sole discretion of the recipient. This material does not contain sufficient information to support an investment decision.
Issued in the UK by AXA Investment Managers UK Limited, which is authorised and regulated by the Financial Conduct Authority in the UK. Registered in England and Wales, No: 01431068. Registered Office: 22 Bishopsgate, London, EC2N 4BQ.
AXA IM and BNPP AM are progressively merging and streamlining our legal entities to create a unified structure
AXA Investment Managers joined BNP Paribas Group in July 2025. Following the merger of AXA Investment Managers Paris and BNP PARIBAS ASSET MANAGEMENT Europe and their respective holding companies on December 31, 2025, the combined company now operates under the BNP PARIBAS ASSET MANAGEMENT Europe name.