

Asia may not follow US rate hikes
The forces keeping the US Federal Reserve in monetary tightening mode have not faded. Diesel and petrol prices remain high, artificial intelligence-driven inflation has not eased, and the labour market remains resilient. Housing market weakness and the recent wobble in AI optimism may make the Fed cautious, but core inflation is still skewed to the upside.
Asian central banks have typically followed the Fed's rate increases. However, it may be different this time unless the Fed's hikes cause significant exchange rate depreciation in the region.
US inflationary pressures remain
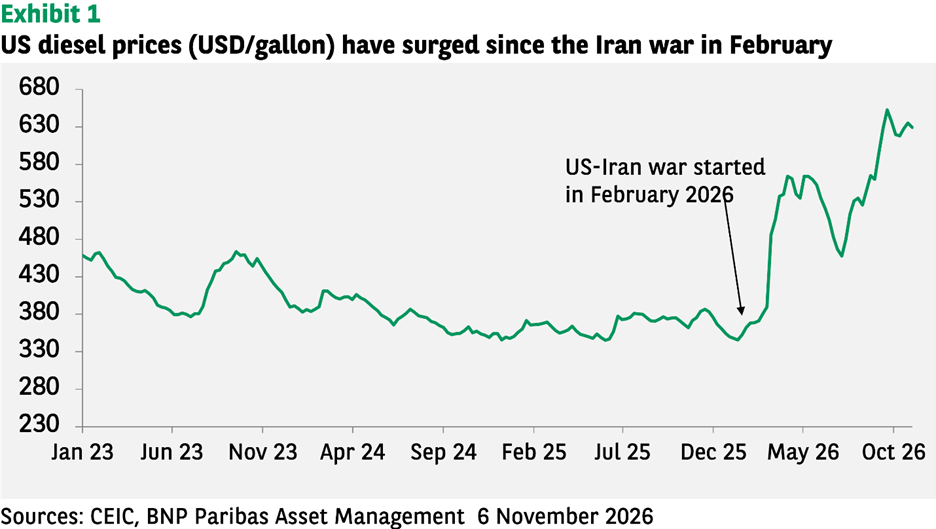
The underlying inflation dynamics in the US have not changed much since the Fed’s rate increase in September. Global energy prices have remained high and tight diesel markets have boosted diesel price inflation (see Exhibit 1). Diesel prices are pivotal to the pass-through to broader inflationary pressures due to the fuel's widespread use in transport, manufacturing and farming.
Fed Chair Kevin Warsh acknowledged recently that tighter financial conditions (due to the rise in bond yields) had helped the Fed to contain inflationary pressures. However, he also stressed that the Fed’s job was to ensure that sector-specific price shocks do not broaden out and that inflation expectations would not be unanchored. So, rising bond yields do not necessarily stand in the way of further rate hikes.
Asia is different
The Fed has already raised rates once in September. October’s stronger-than-expected consumer price index inflation has increased the markets’ conviction of another Fed rate hike in December. Headline inflation came in at 0.4% month-on-month versus the consensus forecast of 0.3% and core CPI was 0.3% versus consensus expectations of 0.2%.
The European Central Bank, the Bank of Japan, the Bank of England and the Bank of Canada have also hiked their rates since September. In Asia (excluding Japan), the picture is more diverse. While a couple of central banks have hiked rates, most have stood pat.
Recent monetary policy cycle experience shows that Asia has not always followed the Fed’s rate moves in lock-step or has followed them with a lag unless the Fed's hikes triggered sharp exchange rate depreciation. Why is that?
Firstly, Asian central banks have a wider set of policy targets than the Fed. They do not follow the Fed if its moves are inconsistent with their own domestic policy needs. Both market experience and Bank for International Settlements research1 show that Asia's regional central banks have 'unwritten targets' including the exchange rate, economic growth and bond yields.
These factors, in turn, affect domestic inflation. Furthermore, the regional authorities also target headline inflation alongside core inflation. All these are different from the Fed-style dual mandates that put core inflation and maximum employment on an equal footing.
Exchange rate is paramount in Asia
Among these policy targets, the exchange rate is of primary importance for Asian authorities. Fed rate hikes widen the interest-rate differential between Asia and the US and if exchange rates depreciate markedly, this could amplify the inflationary effects on the region's economies and financial conditions. To contain that potentially greater impact, the regional central banks will follow the Fed or even react more strongly than the Fed's original move.
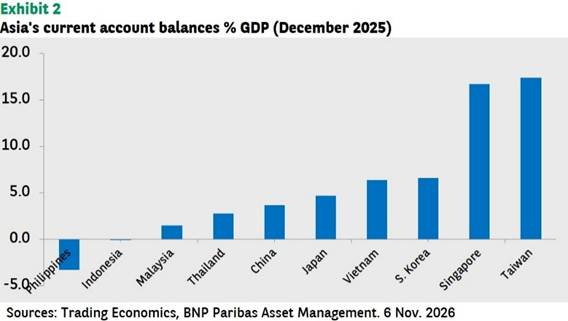
However, other than Indonesia and the Philippines, most of Asia’s economies have large current account surpluses (see Exhibit 2) that provide strong support for the region's exchange rates, thus lessening the pressure to follow the Fed's rate hikes. The recent downward pressures on Asia’s exchange rates mostly reflect a risk-off sentiment arising from the speed and breadth of the global rates sell-off rather than poor fundamentals and wider interest-rate differentials.
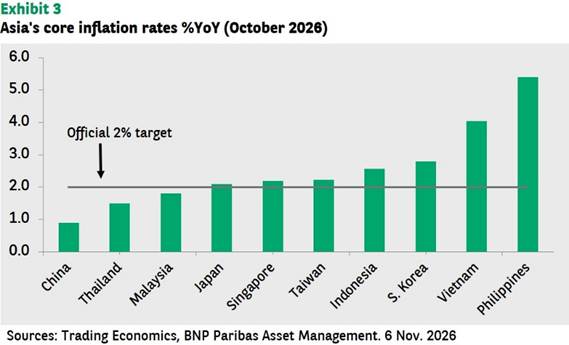
Secondly, despite nine months of high oil prices, core inflation has remained close to, or even lower than, target in most Asian economies, with the notable exceptions of Vietnam and the Philippines (see Exhibit 3). Subsidies have so far helped Asia to contain oil price-induced inflation and the region’s central banks to stay put at low fiscal costs to their treasuries.
However, if the oil shock lasts longer, fiscal pressure will increase and eventually prompt Asian governments to let fuel prices adjust accordingly, unleashing inflationary pressures. This would, in turn, likely prompt regional rate hikes in the wake of those by the Fed.
- {https://www.bis.org/publications/working-paper-770-expansionary-lower-bound-contractionary-monetary-easing-and-trilemma.pdf}
The bottom lines
The macroeconomic backdrop suggests that Asia is far from being in a broad-based interest-rate hike cycle. Policy rates are currently being driven by the impact of rising oil prices on domestic inflation.
A hawkish Fed may lead to a potential tightening bias in Asia, but it will not likely prompt widespread rate hikes unless interest-rate differentials between Asia and the US result in large and persistent regional exchange-rate depreciation.
Data sources: CEIC, Trading Economics, as of 10 November 2026 (unless otherwise stated). Past performance should not be seen as a guide to future returns.


Disclaimer
This document is for informational purposes only and does not constitute investment research or financial analysis relating to transactions in financial instruments as per MIF Directive (2014/65/EU), nor does it constitute on the part of BNP PARIBAS ASSET MANAGEMENT Europe or its affiliated companies an offer to buy or sell any investments, products or services, and should not be considered as solicitation or investment, legal or tax advice, a recommendation for an investment strategy or a personalized recommendation to buy or sell securities.
Due to its simplification, this document is partial and opinions, estimates and forecasts herein are subjective and subject to change without notice. There is no guarantee forecasts made will come to pass. Data, figures, declarations, analysis, predictions and other information in this document is provided based on our state of knowledge at the time of creation of this document. Whilst every care is taken, no representation or warranty (including liability towards third parties), express or implied, is made as to the accuracy, reliability or completeness of the information contained herein. Reliance upon information in this material is at the sole discretion of the recipient. This material does not contain sufficient information to support an investment decision.
Issued in the UK by AXA Investment Managers UK Limited, which is authorised and regulated by the Financial Conduct Authority in the UK. Registered in England and Wales, No: 01431068. Registered Office: 22 Bishopsgate, London, EC2N 4BQ.
AXA IM and BNPP AM are progressively merging and streamlining our legal entities to create a unified structure
AXA Investment Managers joined BNP Paribas Group in July 2025. Following the merger of AXA Investment Managers Paris and BNP PARIBAS ASSET MANAGEMENT Europe and their respective holding companies on December 31, 2025, the combined company now operates under the BNP PARIBAS ASSET MANAGEMENT Europe name.