

Take Two: Tech stocks hit after US midterms; Bank of England hikes interest rates
What do you need to know?
Stocks fell sharply last week following the results of the US midterm elections as concerns escalated over whether there would be a slowdown in artificial intelligence development. The S&P 500 index dropped by 5% while the tech-heavy Nasdaq declined 7% in the week to Thursday’s close*. Japan’s Nikkei fell 6% while Europe’s Stoxx 600 index gained 1%. US stocks initially rallied after the Democrats won control of Congress in the midterm elections, but unease subsequently grew over potentially tighter controls on data centres, and if restrictions could be put on AI advancement.
*In US dollar terms. Source: FactSet, data as of 5 November 2026
Around the world
The Bank of England raised UK interest rates by 25 basis points to 4%, its first hike in more than three years. Eight of the nine policymakers voted for this increase, while one opted for a 50bp hike. The central bank said the increase was due to the “degree of inflationary pressure in the pipeline”. BoE Governor Andrew Bailey warned that unless the Middle East conflict is resolved, the rate hike was not likely “to be the last”. Elsewhere, the Reserve Bank of Australia raised interest rates by 25bp to 4.85%, the fifth hike this year, and the highest level since 2008.
Figure in focus: 4.0%
Eurozone annual inflation rose to a three-year high in October, as the Middle East conflict continued to push up energy prices. Inflation rose to 4.0% from 3.8% in September, an official flash estimate showed, driven by a near-21% surge in the energy component. Excluding energy, food, alcohol and tobacco, core inflation remained steady at 2.5%. The data added to expectations that the European Central Bank will raise interest rates at its next meeting in December.
Chart of the week
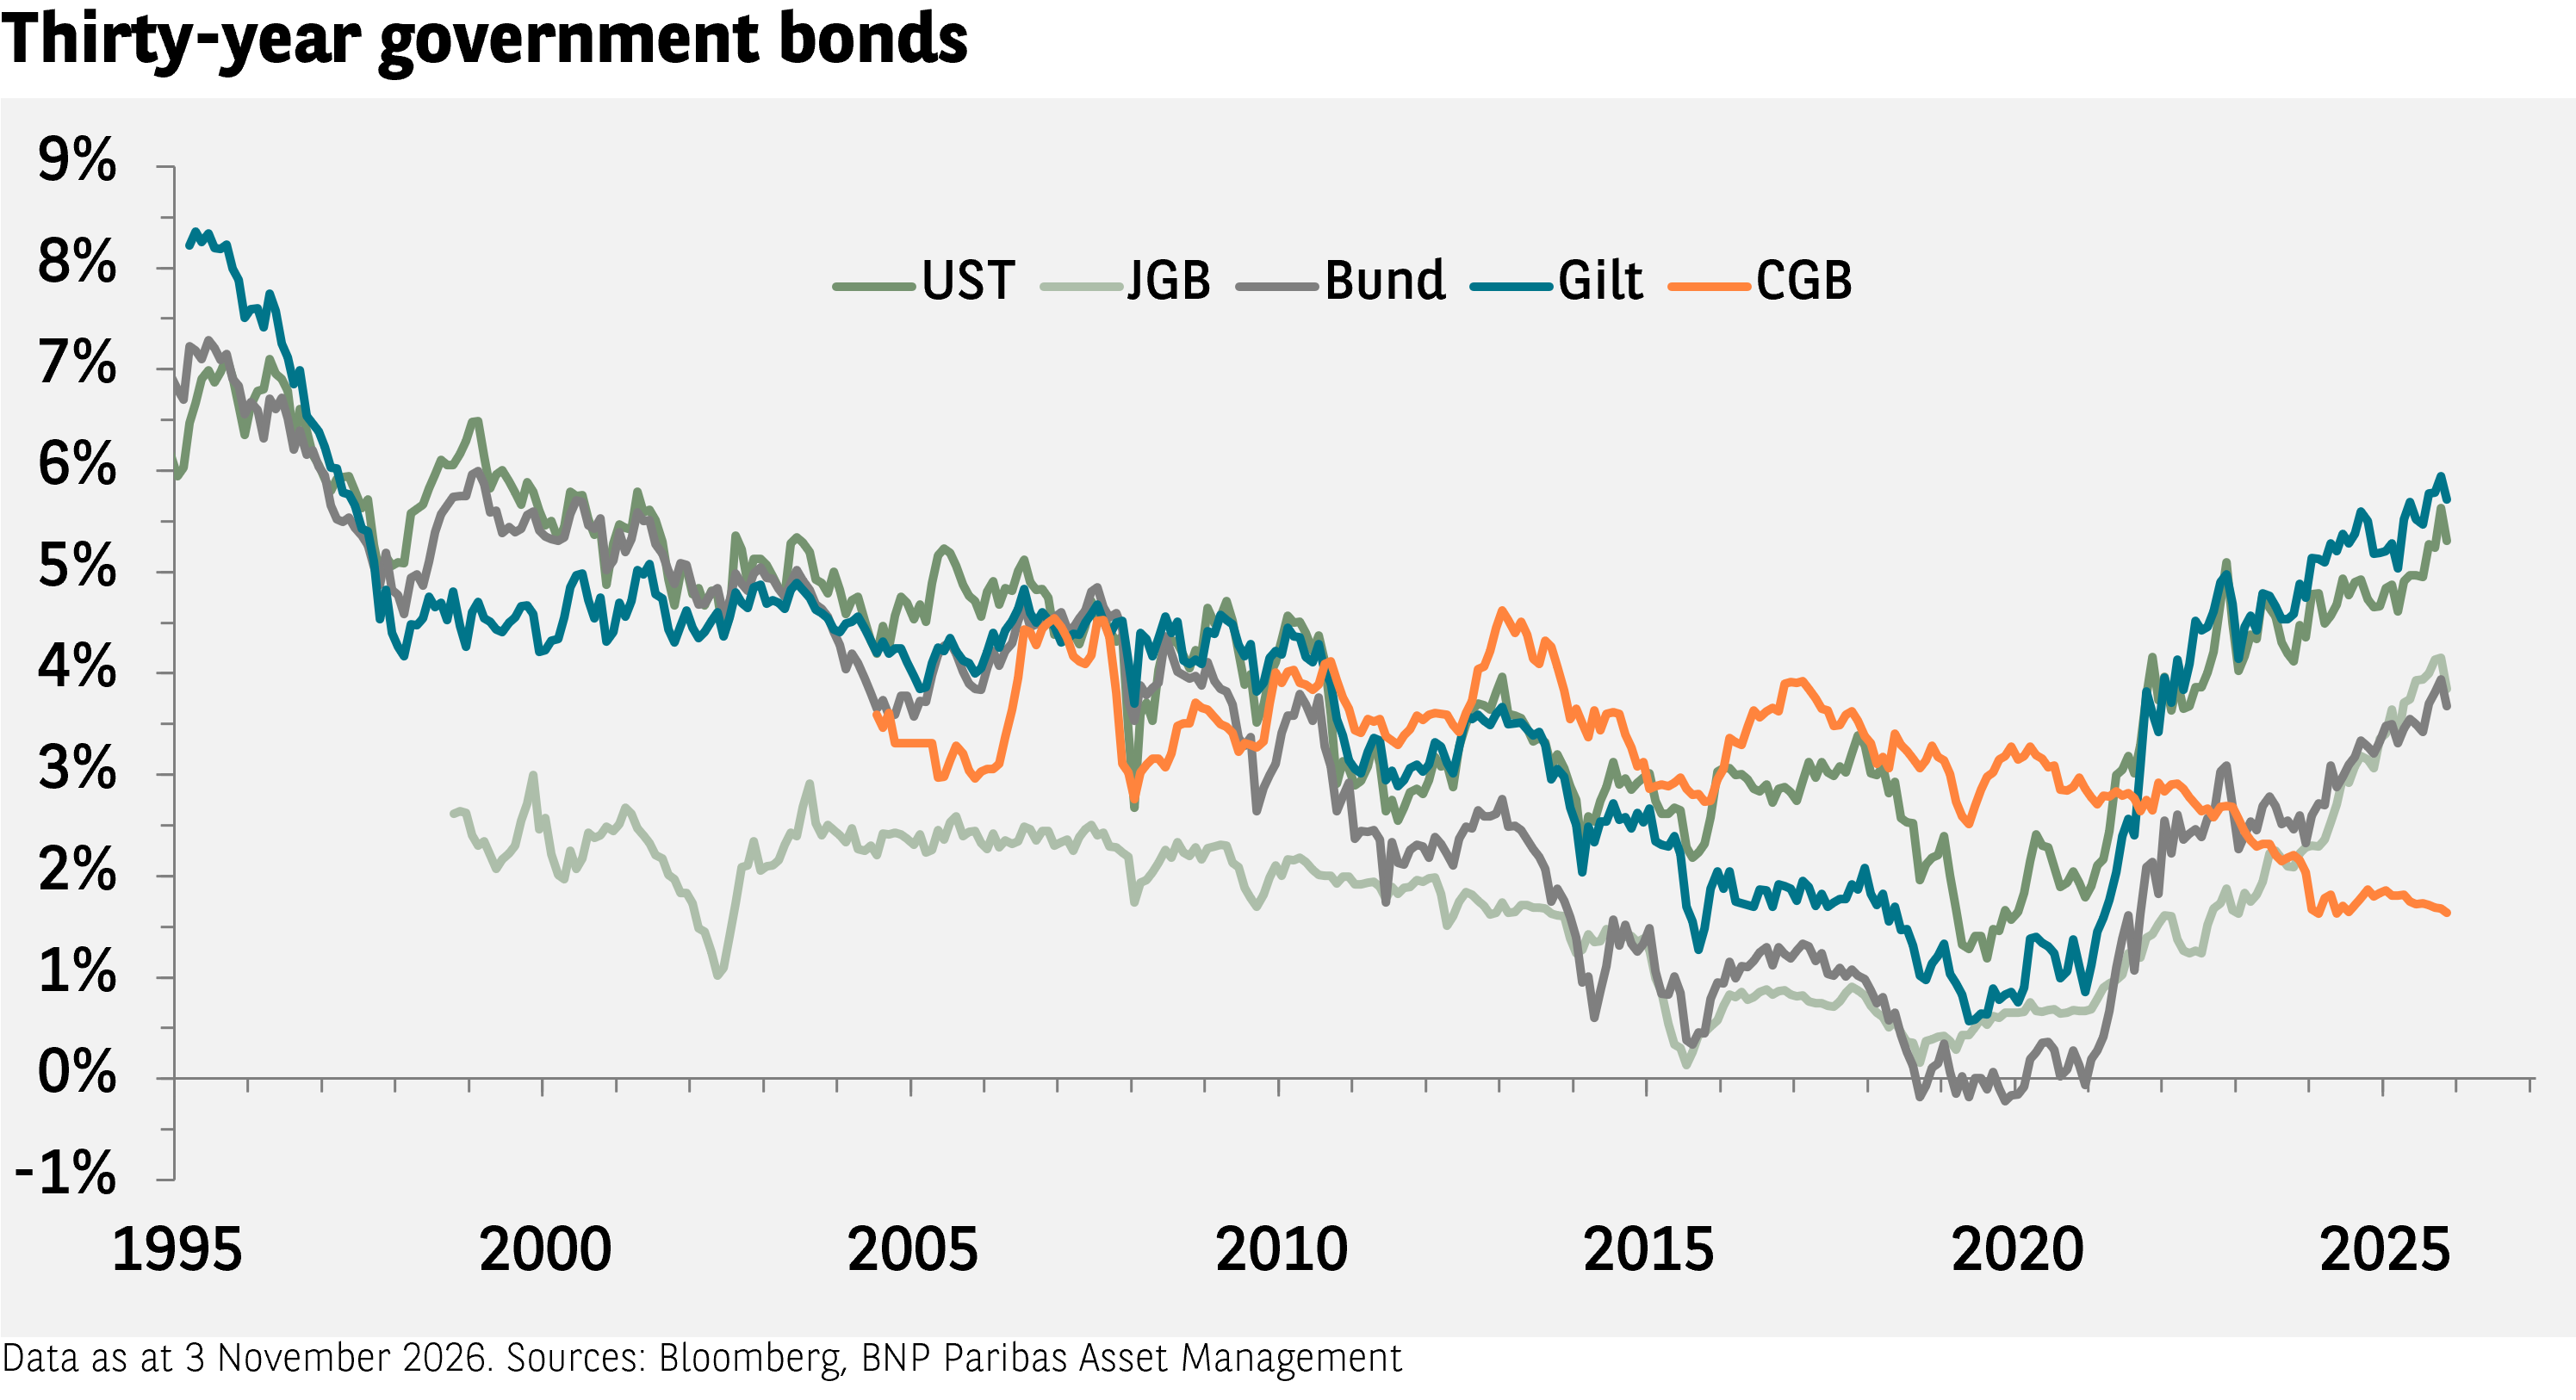
Long-dated bond yields have been on the rise for the past six years, translating to higher borrowing costs for governments and companies. For example, 30-year German government bond yields have increased by almost 400bp after hitting all-time lows during the pandemic. This upward direction is shared across all major advanced economies, with the exception of China. Both cyclical factors – higher than expected inflation and monetary policy tightening – and structural factors like persistent public deficits have contributed to this rise in long-dated yields.
Words of wisdom: Cryosphere
The cryosphere – the parts of the Earth’s surface that are covered by water in a solid state, including ice and snow – faces permanent damage if the Paris Agreement’s 1.5°C climate change target is exceeded. Overshooting this goal will bring “large-scale, and in many cases irreversible,” impacts, such as rising sea levels and water shortages as glaciers disappear, according to a new report from the United Nations. It called for increased emissions reductions as well as more financing for climate change adaptation.
What’s coming up?
On Monday, China publishes its latest inflation rate, followed by trade data on Tuesday. Tuesday also sees the US report inflation data for October – US inflation rose more than expected to 3.7% in September. On Thursday, the UK issues a preliminary estimate of its third quarter GDP growth rate. On Friday, the eurozone publishes a second estimate of its own Q3 GDP growth rate.
Read more insights on Viewpoint


Disclaimer
This document is for informational purposes only and does not constitute investment research or financial analysis relating to transactions in financial instruments as per MIF Directive (2014/65/EU), nor does it constitute on the part of BNP PARIBAS ASSET MANAGEMENT Europe or its affiliated companies an offer to buy or sell any investments, products or services, and should not be considered as solicitation or investment, legal or tax advice, a recommendation for an investment strategy or a personalized recommendation to buy or sell securities.
Due to its simplification, this document is partial and opinions, estimates and forecasts herein are subjective and subject to change without notice. There is no guarantee forecasts made will come to pass. Data, figures, declarations, analysis, predictions and other information in this document is provided based on our state of knowledge at the time of creation of this document. Whilst every care is taken, no representation or warranty (including liability towards third parties), express or implied, is made as to the accuracy, reliability or completeness of the information contained herein. Reliance upon information in this material is at the sole discretion of the recipient. This material does not contain sufficient information to support an investment decision.
Issued in the UK by AXA Investment Managers UK Limited, which is authorised and regulated by the Financial Conduct Authority in the UK. Registered in England and Wales, No: 01431068. Registered Office: 22 Bishopsgate, London, EC2N 4BQ.
AXA IM and BNPP AM are progressively merging and streamlining our legal entities to create a unified structure
AXA Investment Managers joined BNP Paribas Group in July 2025. Following the merger of AXA Investment Managers Paris and BNP PARIBAS ASSET MANAGEMENT Europe and their respective holding companies on December 31, 2025, the combined company now operates under the BNP PARIBAS ASSET MANAGEMENT Europe name.