

Take Two: US equities enjoy record inflows; eurozone inflation rises
What do you need to know?
Overseas investors put a record $942 billion into US equities and investment fund shares in the year to July, according to official data cited by the Financial Times. The surge in investment came alongside strong gains for US stock markets. The US blue-chip S&P 500 index is up 13% year-to-date while the tech-heavy Nasdaq has risen 16%.* Elsewhere, the US economy grew faster than initially thought in the second quarter of this year. GDP growth was revised up to 2.2% on an annualised basis from the previous estimate of 1.5%, but was still down from Q1’s 2.5% rate.
*In US dollar terms. Source: FactSet, data as of 1 October 2026
Around the world
Inflation in the eurozone rose to 3.8% in September from 3.2% in August, its highest level in three years, a flash estimate showed. The increase was driven by rising energy prices. Core inflation, which excludes more volatile energy, food, alcohol and tobacco prices, rose slightly to 2.5% from 2.4%. Separately, eurozone consumers are less confident about the economic outlook, a new survey showed. The eurozone economic sentiment indicator fell to 97.9 in September from 98.4 in August, its first decline since April.
Figure in focus: 6%
The yield on UK 30-year government bonds hit the 6% threshold last week for the first time since 1998, pushing up the country’s official borrowing costs. Bond yields move inversely to prices – concerns over inflation and higher interest rates as the Middle East conflict continues have prompted a global bond sell-off. US 10-year Treasury yields also hit fresh multi-decade highs last week while yields on long-term Japanese government debt also rose.
Chart of the week
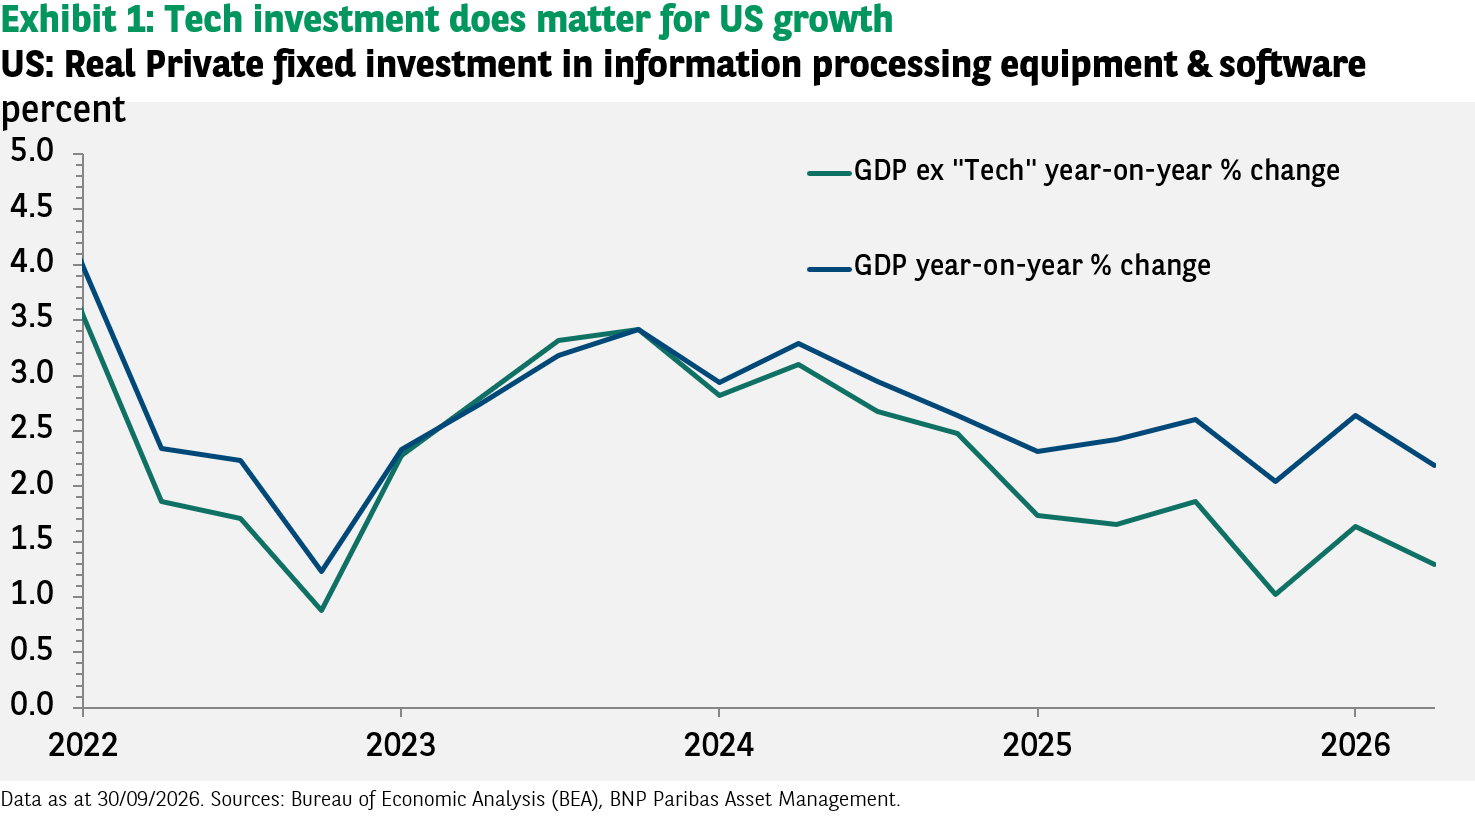
The artificial intelligence investment boom can be difficult to properly illustrate. However, a rudimentary, yet telling and readily available, metric can be derived from the US national accounts. The “private fixed investment in information processing equipment and software” component illustrates the AI investment momentum. It represents 7% of GDP and 45% of non-residential private fixed investment, compared to 35% three years ago and 25% in 2015. Excluding this component reveals that economic growth would have been significantly lower in recent quarters. In 2025, tech contributed 41% of GDP growth, compared to an average of 10% from 2011 to 2019 (according to BNP Paribas Asset Management calculations based on official data).
Words of wisdom: Ground-level ozone
A secondary pollutant that comes from chemical reactions stemming from fossil fuels and triggered by sunlight and high temperatures. Around 50% of the global population was exposed to very poor, or extremely poor, air quality due to ozone concentration so far in 2026, according to the Copernicus Atmosphere Monitoring Service. Only 5% of the global population was exposed to “good” long-term ozone levels, the analysis found. Ozone concentration is affected by climate change with pollution levels higher during the extreme summer heatwaves experienced in Europe, for example.
What’s coming up?
On Monday, final composite Purchasing Managers’ Indices data is released covering business activity in the eurozone, UK, US and Japan. Wednesday sees the Federal Reserve publish the minutes of its latest policy meeting where it voted to raise interest rates by 25 basis points. This marked its first hike since July 2023. On Friday, Canada issues its latest unemployment figures.
Read more insights on Viewpoint

Disclaimer
This document is for informational purposes only and does not constitute investment research or financial analysis relating to transactions in financial instruments as per MIF Directive (2014/65/EU), nor does it constitute on the part of BNP PARIBAS ASSET MANAGEMENT Europe or its affiliated companies an offer to buy or sell any investments, products or services, and should not be considered as solicitation or investment, legal or tax advice, a recommendation for an investment strategy or a personalized recommendation to buy or sell securities.
Due to its simplification, this document is partial and opinions, estimates and forecasts herein are subjective and subject to change without notice. There is no guarantee forecasts made will come to pass. Data, figures, declarations, analysis, predictions and other information in this document is provided based on our state of knowledge at the time of creation of this document. Whilst every care is taken, no representation or warranty (including liability towards third parties), express or implied, is made as to the accuracy, reliability or completeness of the information contained herein. Reliance upon information in this material is at the sole discretion of the recipient. This material does not contain sufficient information to support an investment decision.
Issued in the UK by AXA Investment Managers UK Limited, which is authorised and regulated by the Financial Conduct Authority in the UK. Registered in England and Wales, No: 01431068. Registered Office: 22 Bishopsgate, London, EC2N 4BQ.
AXA IM and BNPP AM are progressively merging and streamlining our legal entities to create a unified structure
AXA Investment Managers joined BNP Paribas Group in July 2025. Following the merger of AXA Investment Managers Paris and BNP PARIBAS ASSET MANAGEMENT Europe and their respective holding companies on December 31, 2025, the combined company now operates under the BNP PARIBAS ASSET MANAGEMENT Europe name.