

Seizing the euro fixed income opportunity with flexibility and diversification
KEY POINTS
Europe’s fixed income landscape has undergone significant changes in recent years and become a segment difficult to ignore within the global bond universe.
While recent market volatility has sent yields higher – 10-year German bonds are at multi-year highs – we believe this represents a significant opportunity.
Yet these valuations have not been reached by accident. Rising geopolitical risks and subsequent energy shocks have weighed on inflation and central banks’ monetary policies.
Ultimately global fiscal slippage led to higher sovereign debts and deficits. While these factors may still be a source of volatility, we believe investors should not ignore the attractive yield euro-denominated fixed income currently offers, especially when managed with an active, flexible and diversified approach.
Higher yields mean higher potential return
Imagine a 100-metre sprint where competitors start at different distances from the finish line. All being equal, those closer to the end line will enjoy much greater odds of winning.
The same applies to bond markets. While past performance does not guarantee future returns, history has shown nonetheless that higher rates at the beginning of the investing period have generally been associated with higher returns.
The charts below show how starting yields have been a strong driver of three-year annualised returns for the euro aggregate universe over the past 25 years (Exhibit 1).
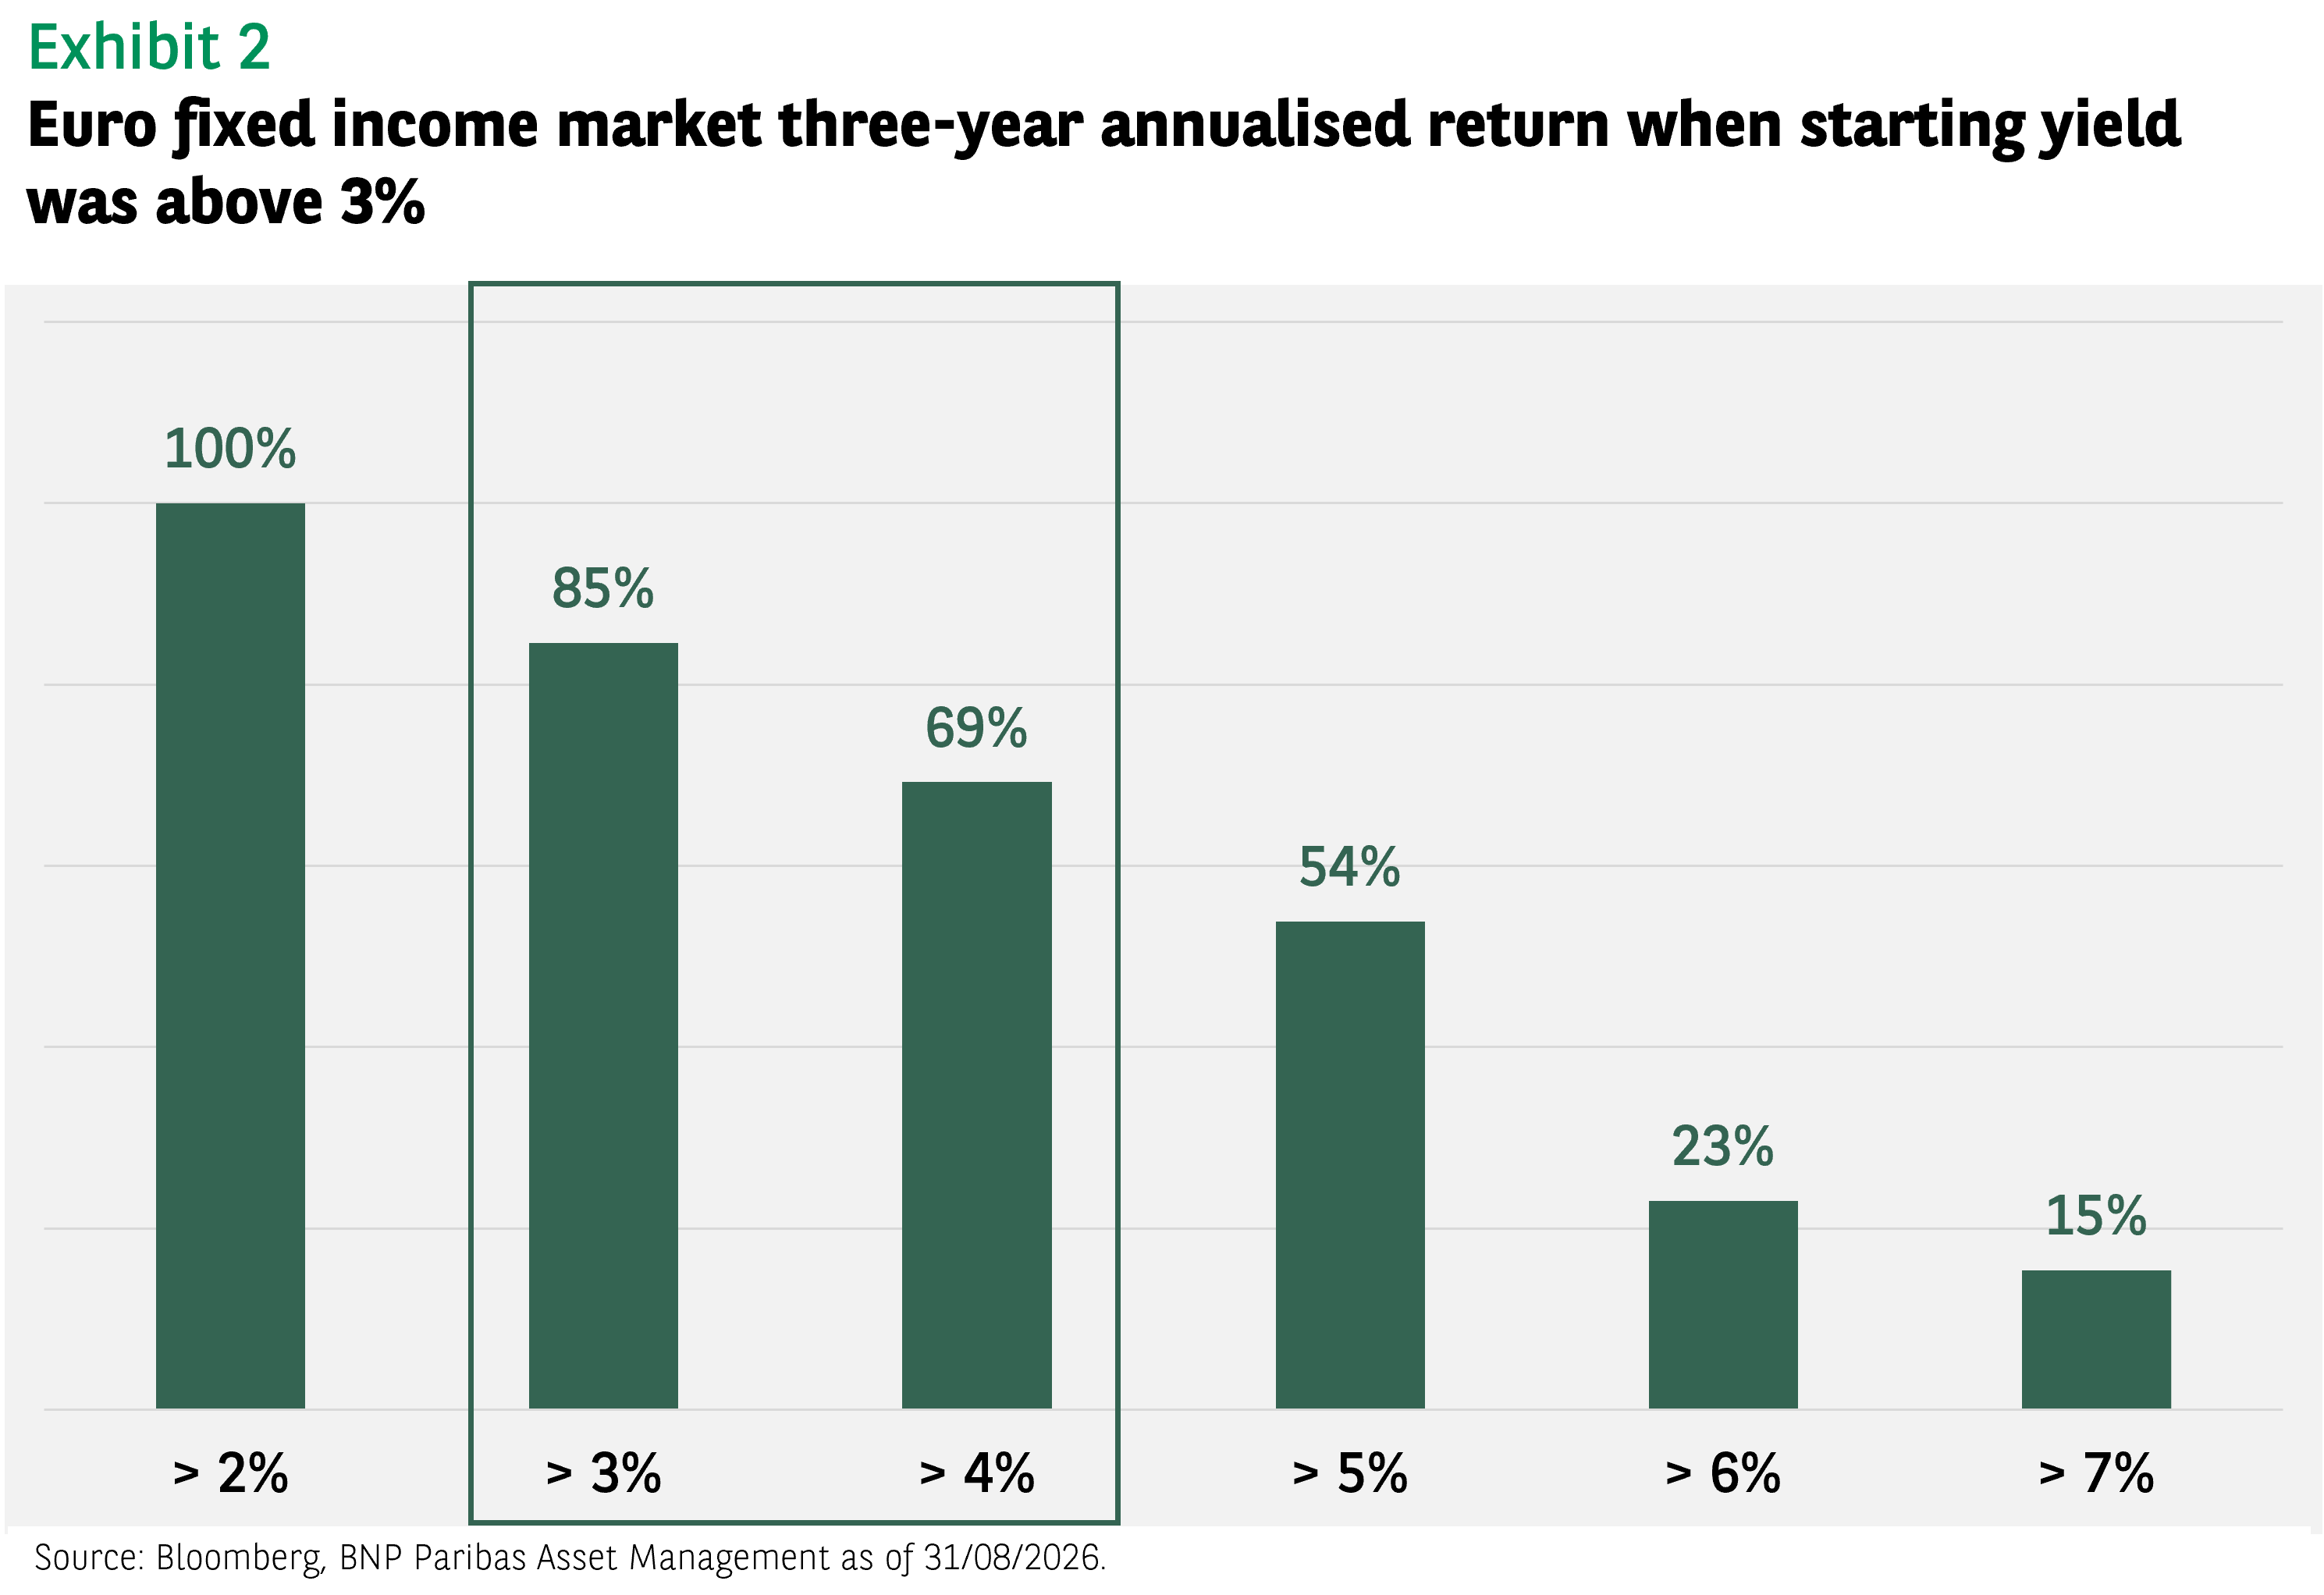
Actually, when the euro fixed income average yield was above 3% as it is now, the three-year annualised returns have been above 3%, nine times out of 10, and above 4%, seven times out of 10 (Exhibit 2).
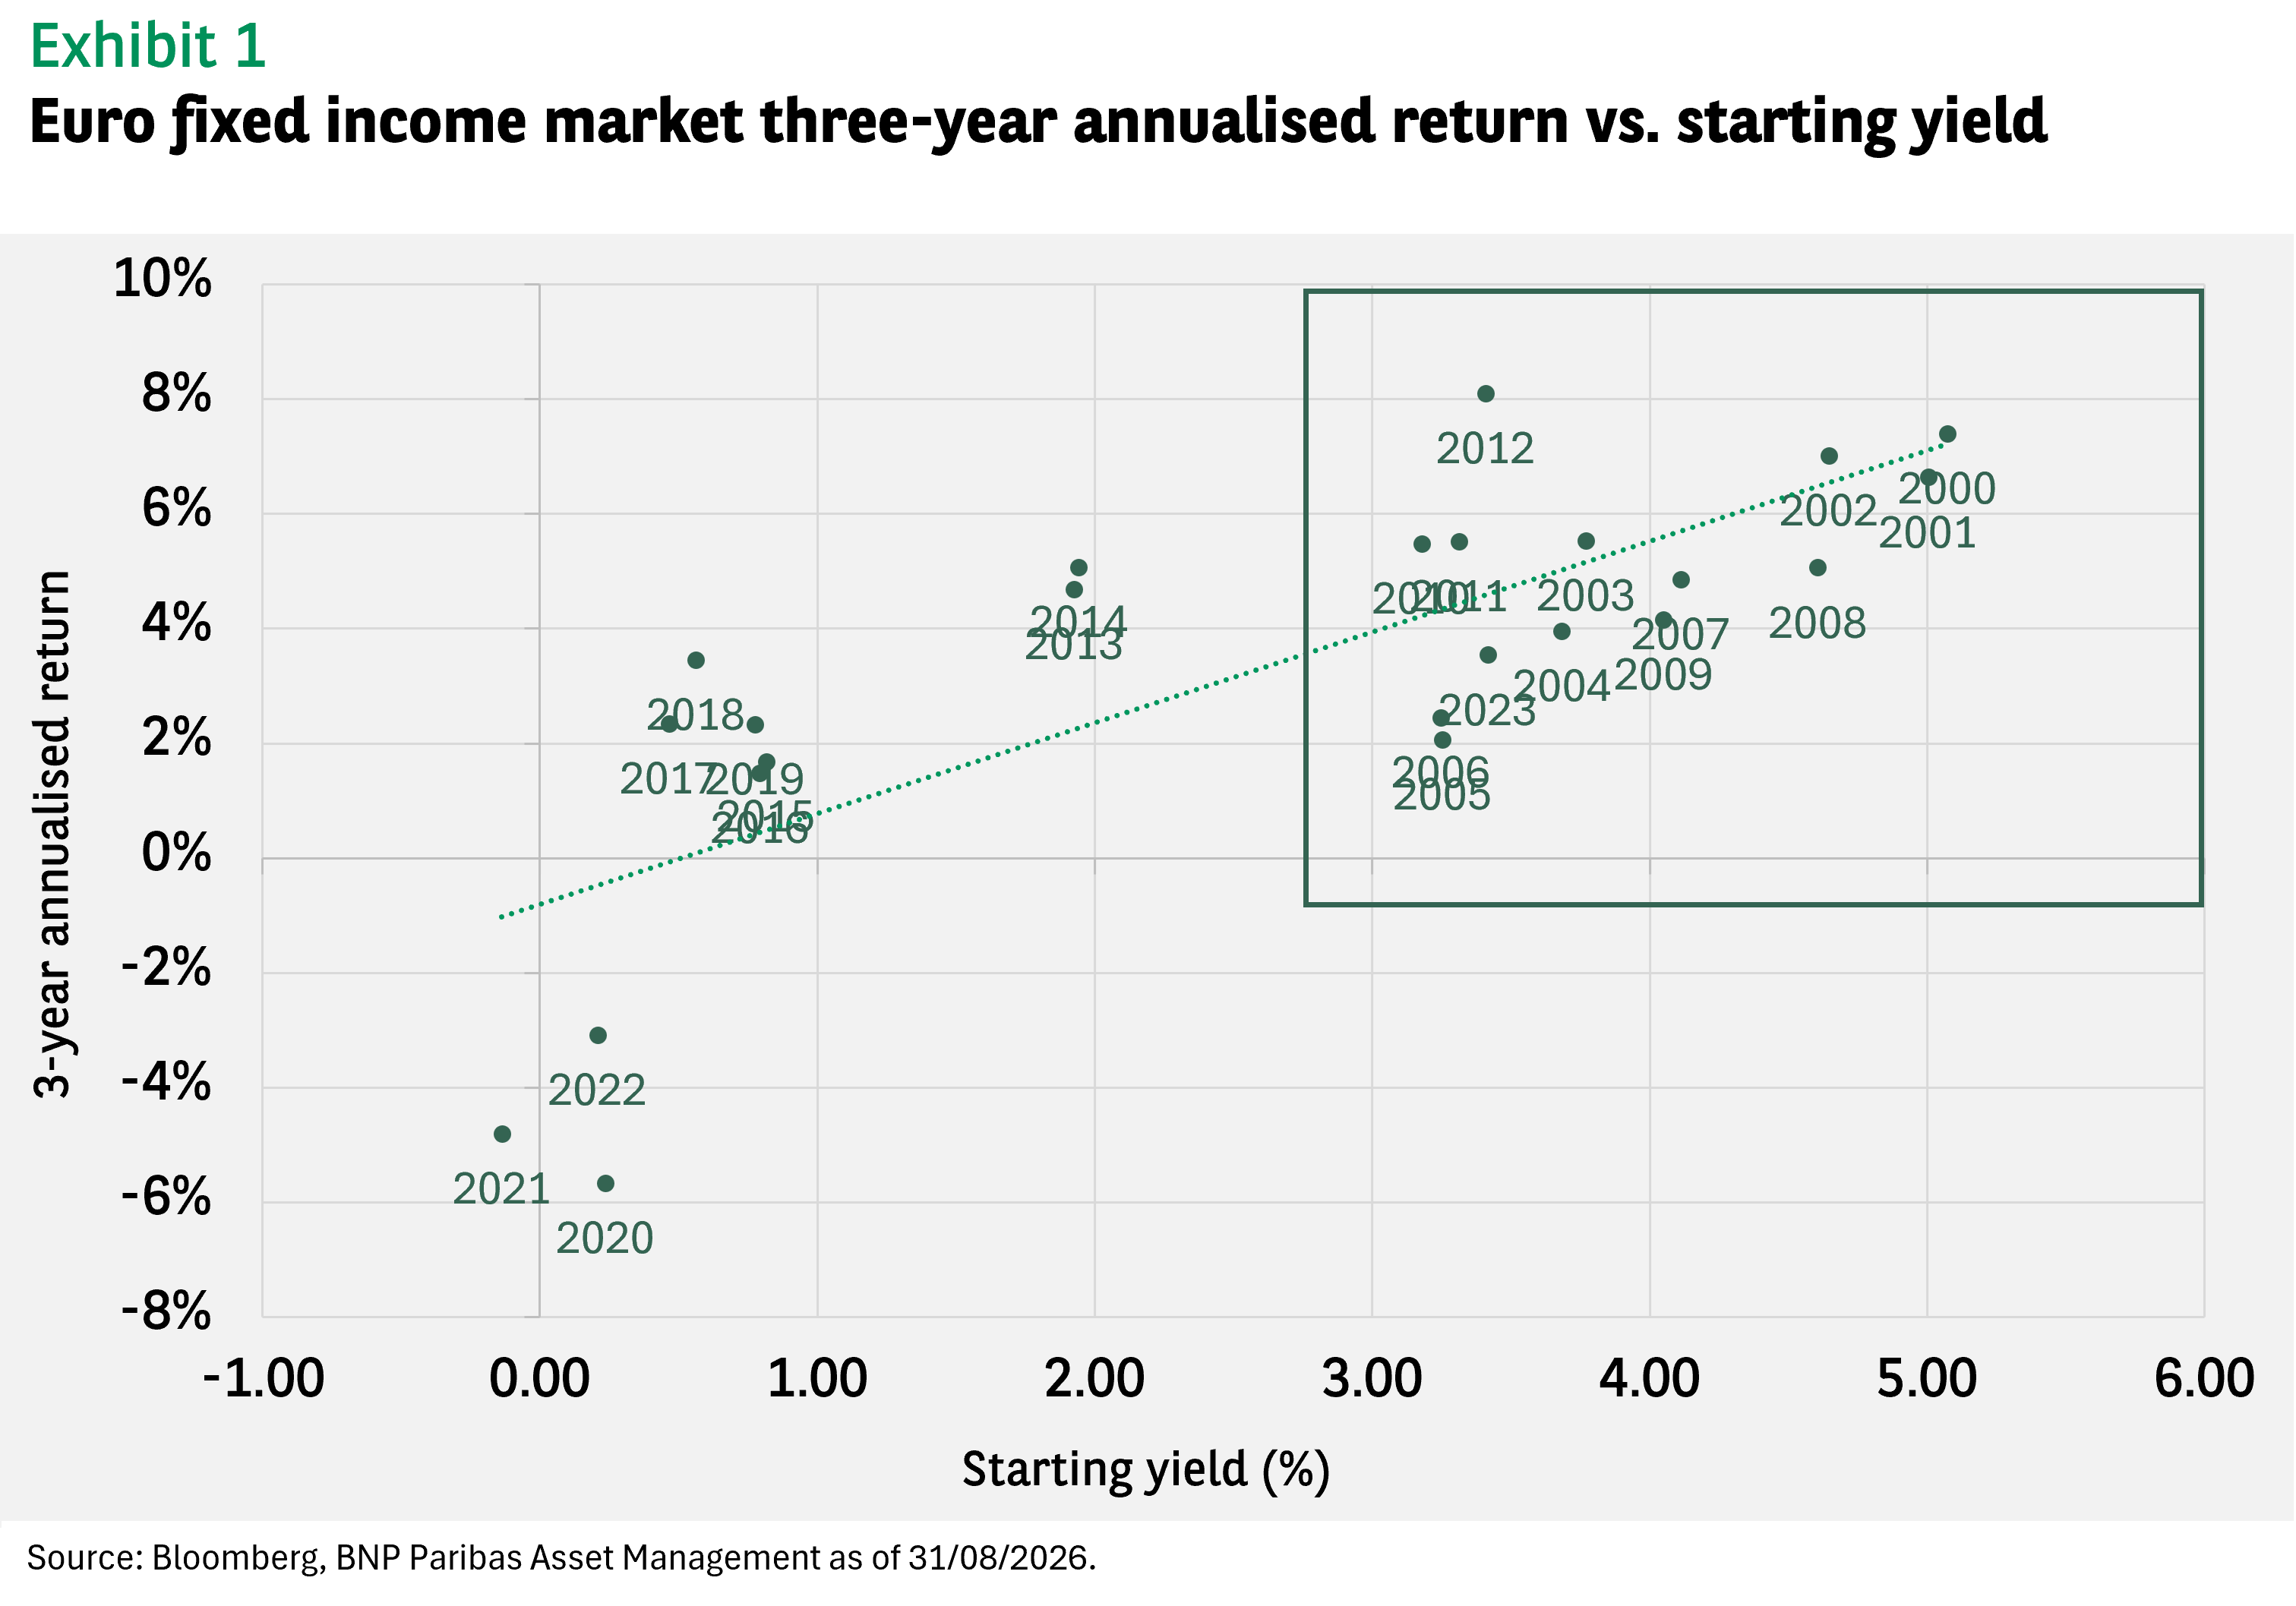
But this is not a surprise: bond market performance over a given period is driven by the starting yield (what we can also call the carry) and the yield’s trajectory over the period. Hence, the higher the yield, the higher the potential performance (provided the rise in yield does not erase that advance).
Indeed, a significant rise in yield could potentially wipe out the entire carry of an investor’s fixed income allocation. Yet again it is quite interesting that over the past 30 years we have had only three cases of negative performance over a three-year period and they all include the 2022 massive bond market sell-off that started from a very low level of yield. There is an explanation for that: higher yields mean a greater buffer against rising interest rates.
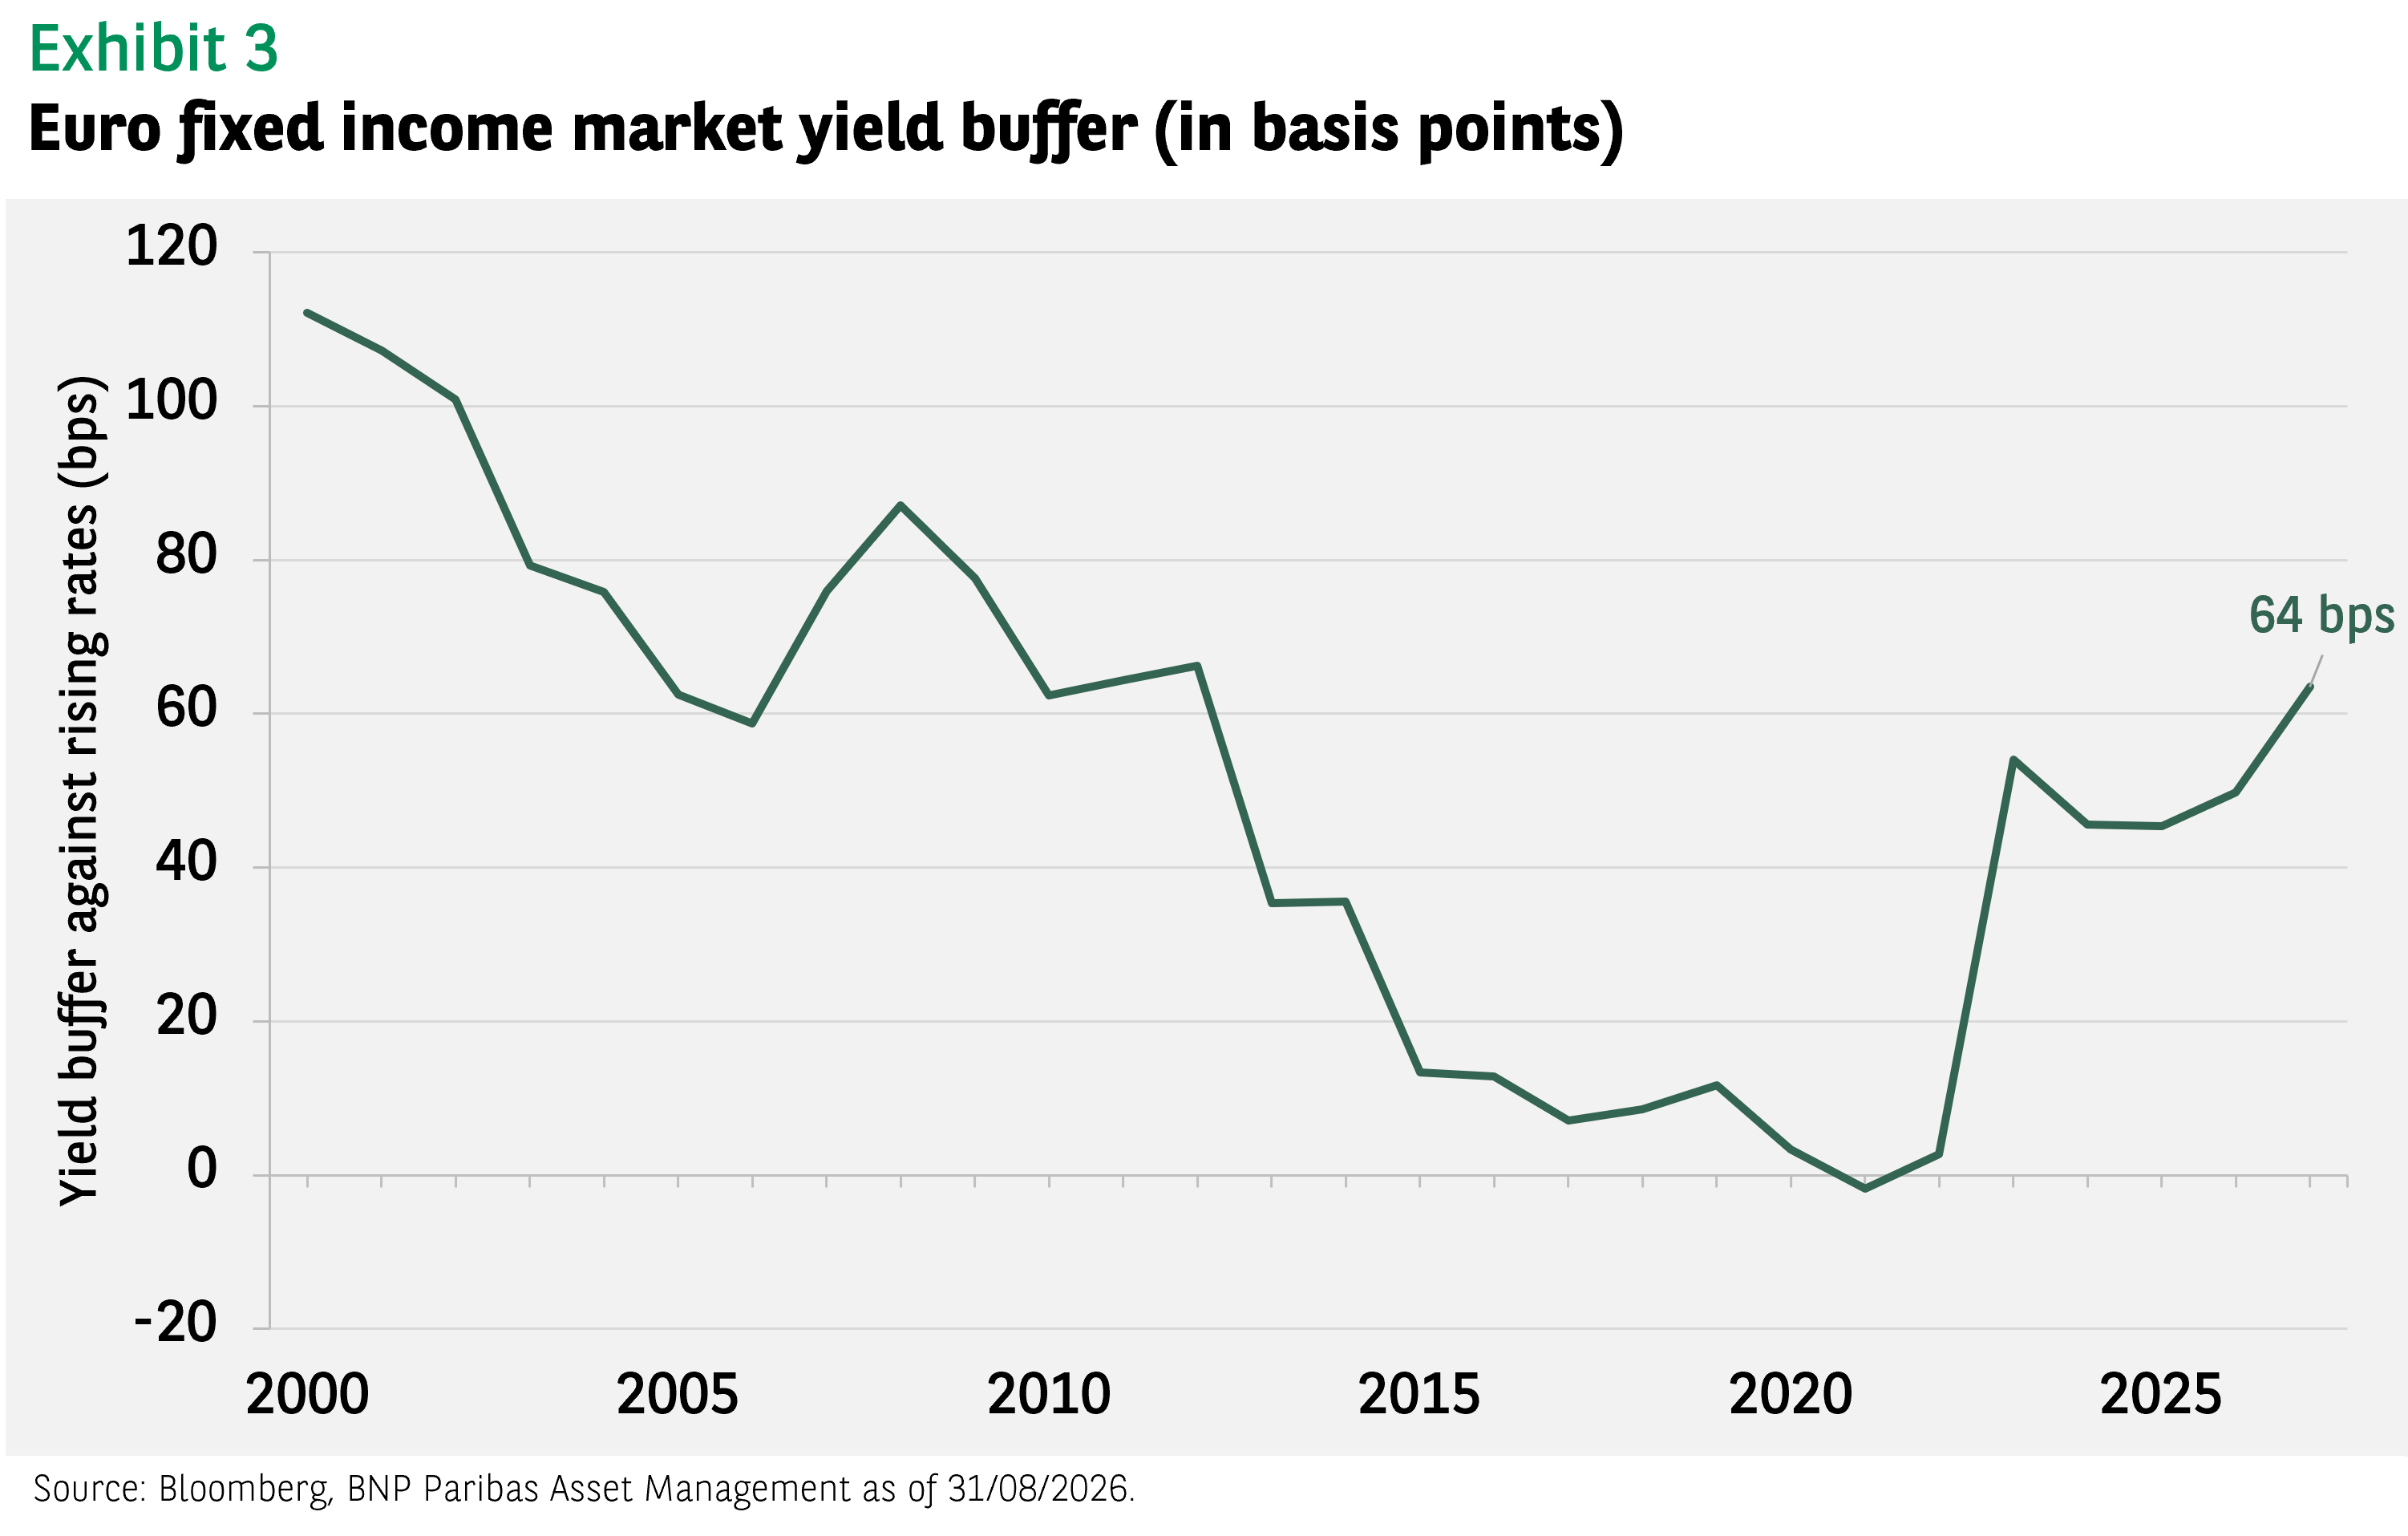
While the quantitative easing era left Europe’s fixed income market without any ammunition against rising interest rates (with the buffer at or close to zero from 2015 to 2022) the recent repricing has reloaded the universe to a level not seen for more than a decade.
Currently, we believe the euro fixed income market can withstand about 60 basis points of rebound in rates before potentially generating a negative return.
Simply put, not only do current valuations provide some buffer against rising rates but they also tend to be associated historically with higher returns.
Higher volatility can be a source of opportunity
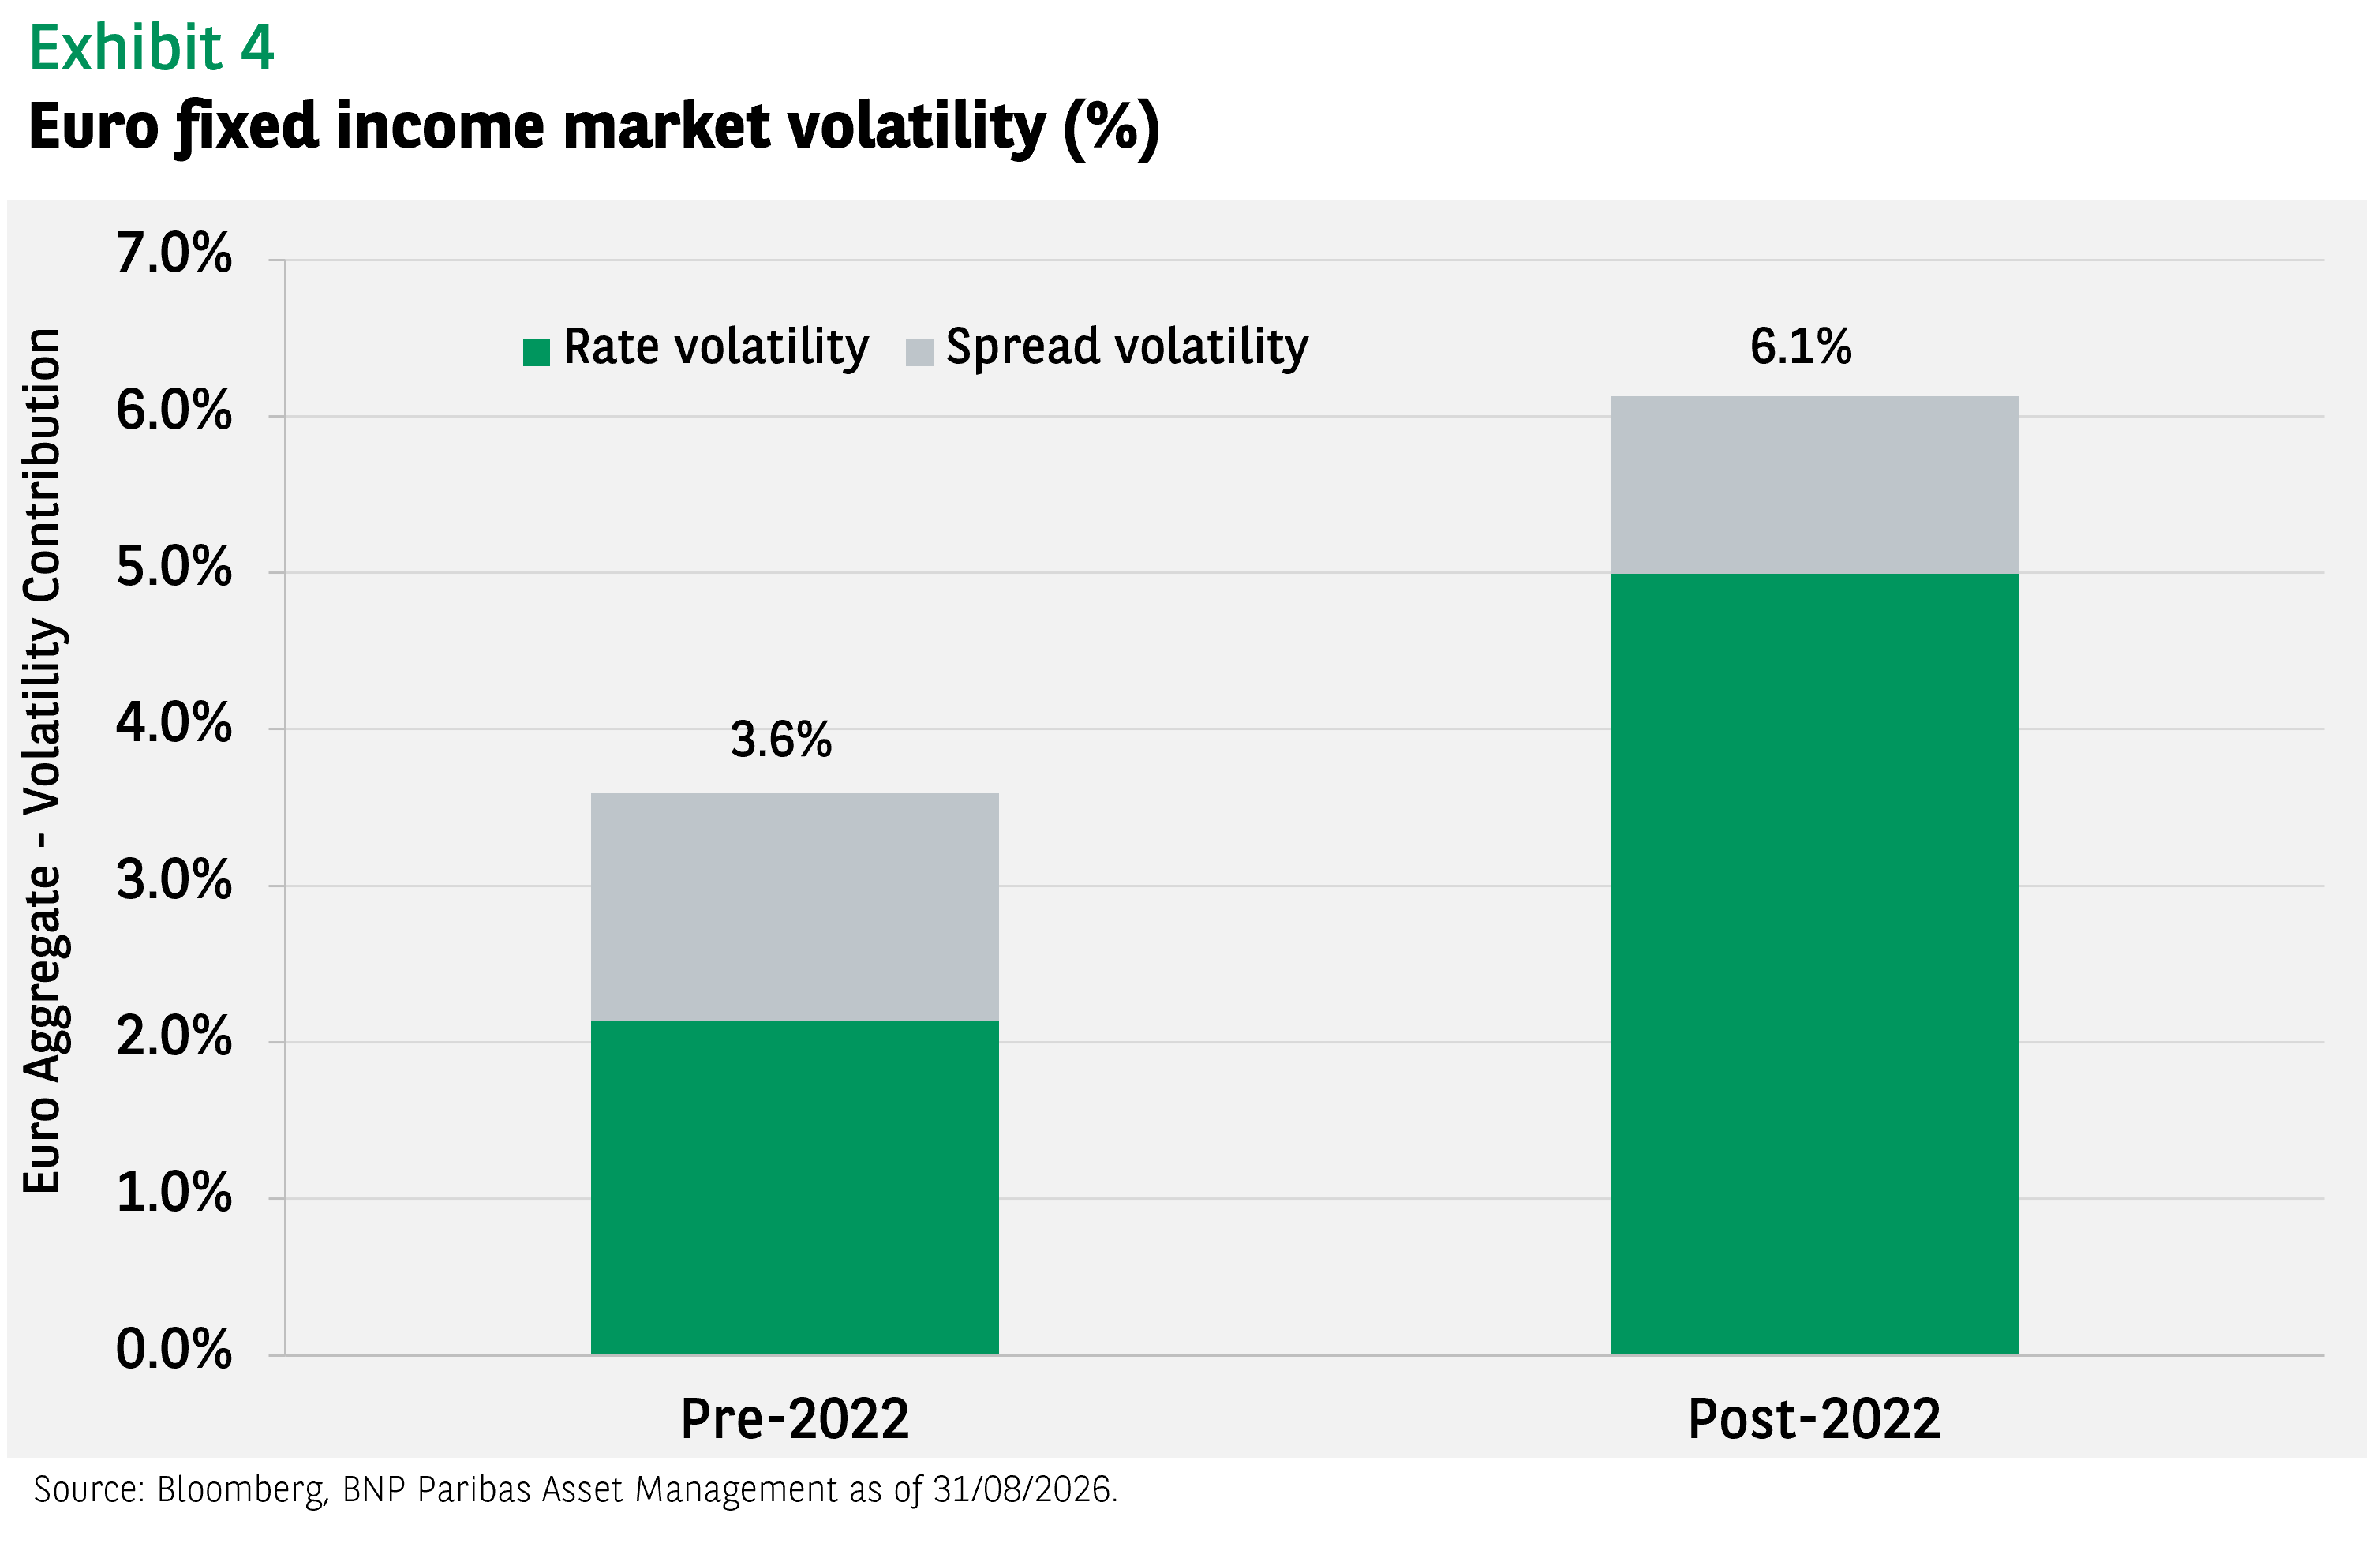
Over recent years, the market has witnessed more volatility, and the current environment should continue to fuel this. Yet it is interesting to note that this new regime of volatility has been driven mostly by interest rates rather than spread volatility.
In other words, rates might be higher but at the expense of higher volatility while tighter credit spreads over recent years have been accompanied by a declining spread volatility.
From a risk-adjusted perspective, this might make current rates valuations less attractive and investors reluctant to take on additional duration risk. But from an active management perspective, we believe such volatility is an opportunity.
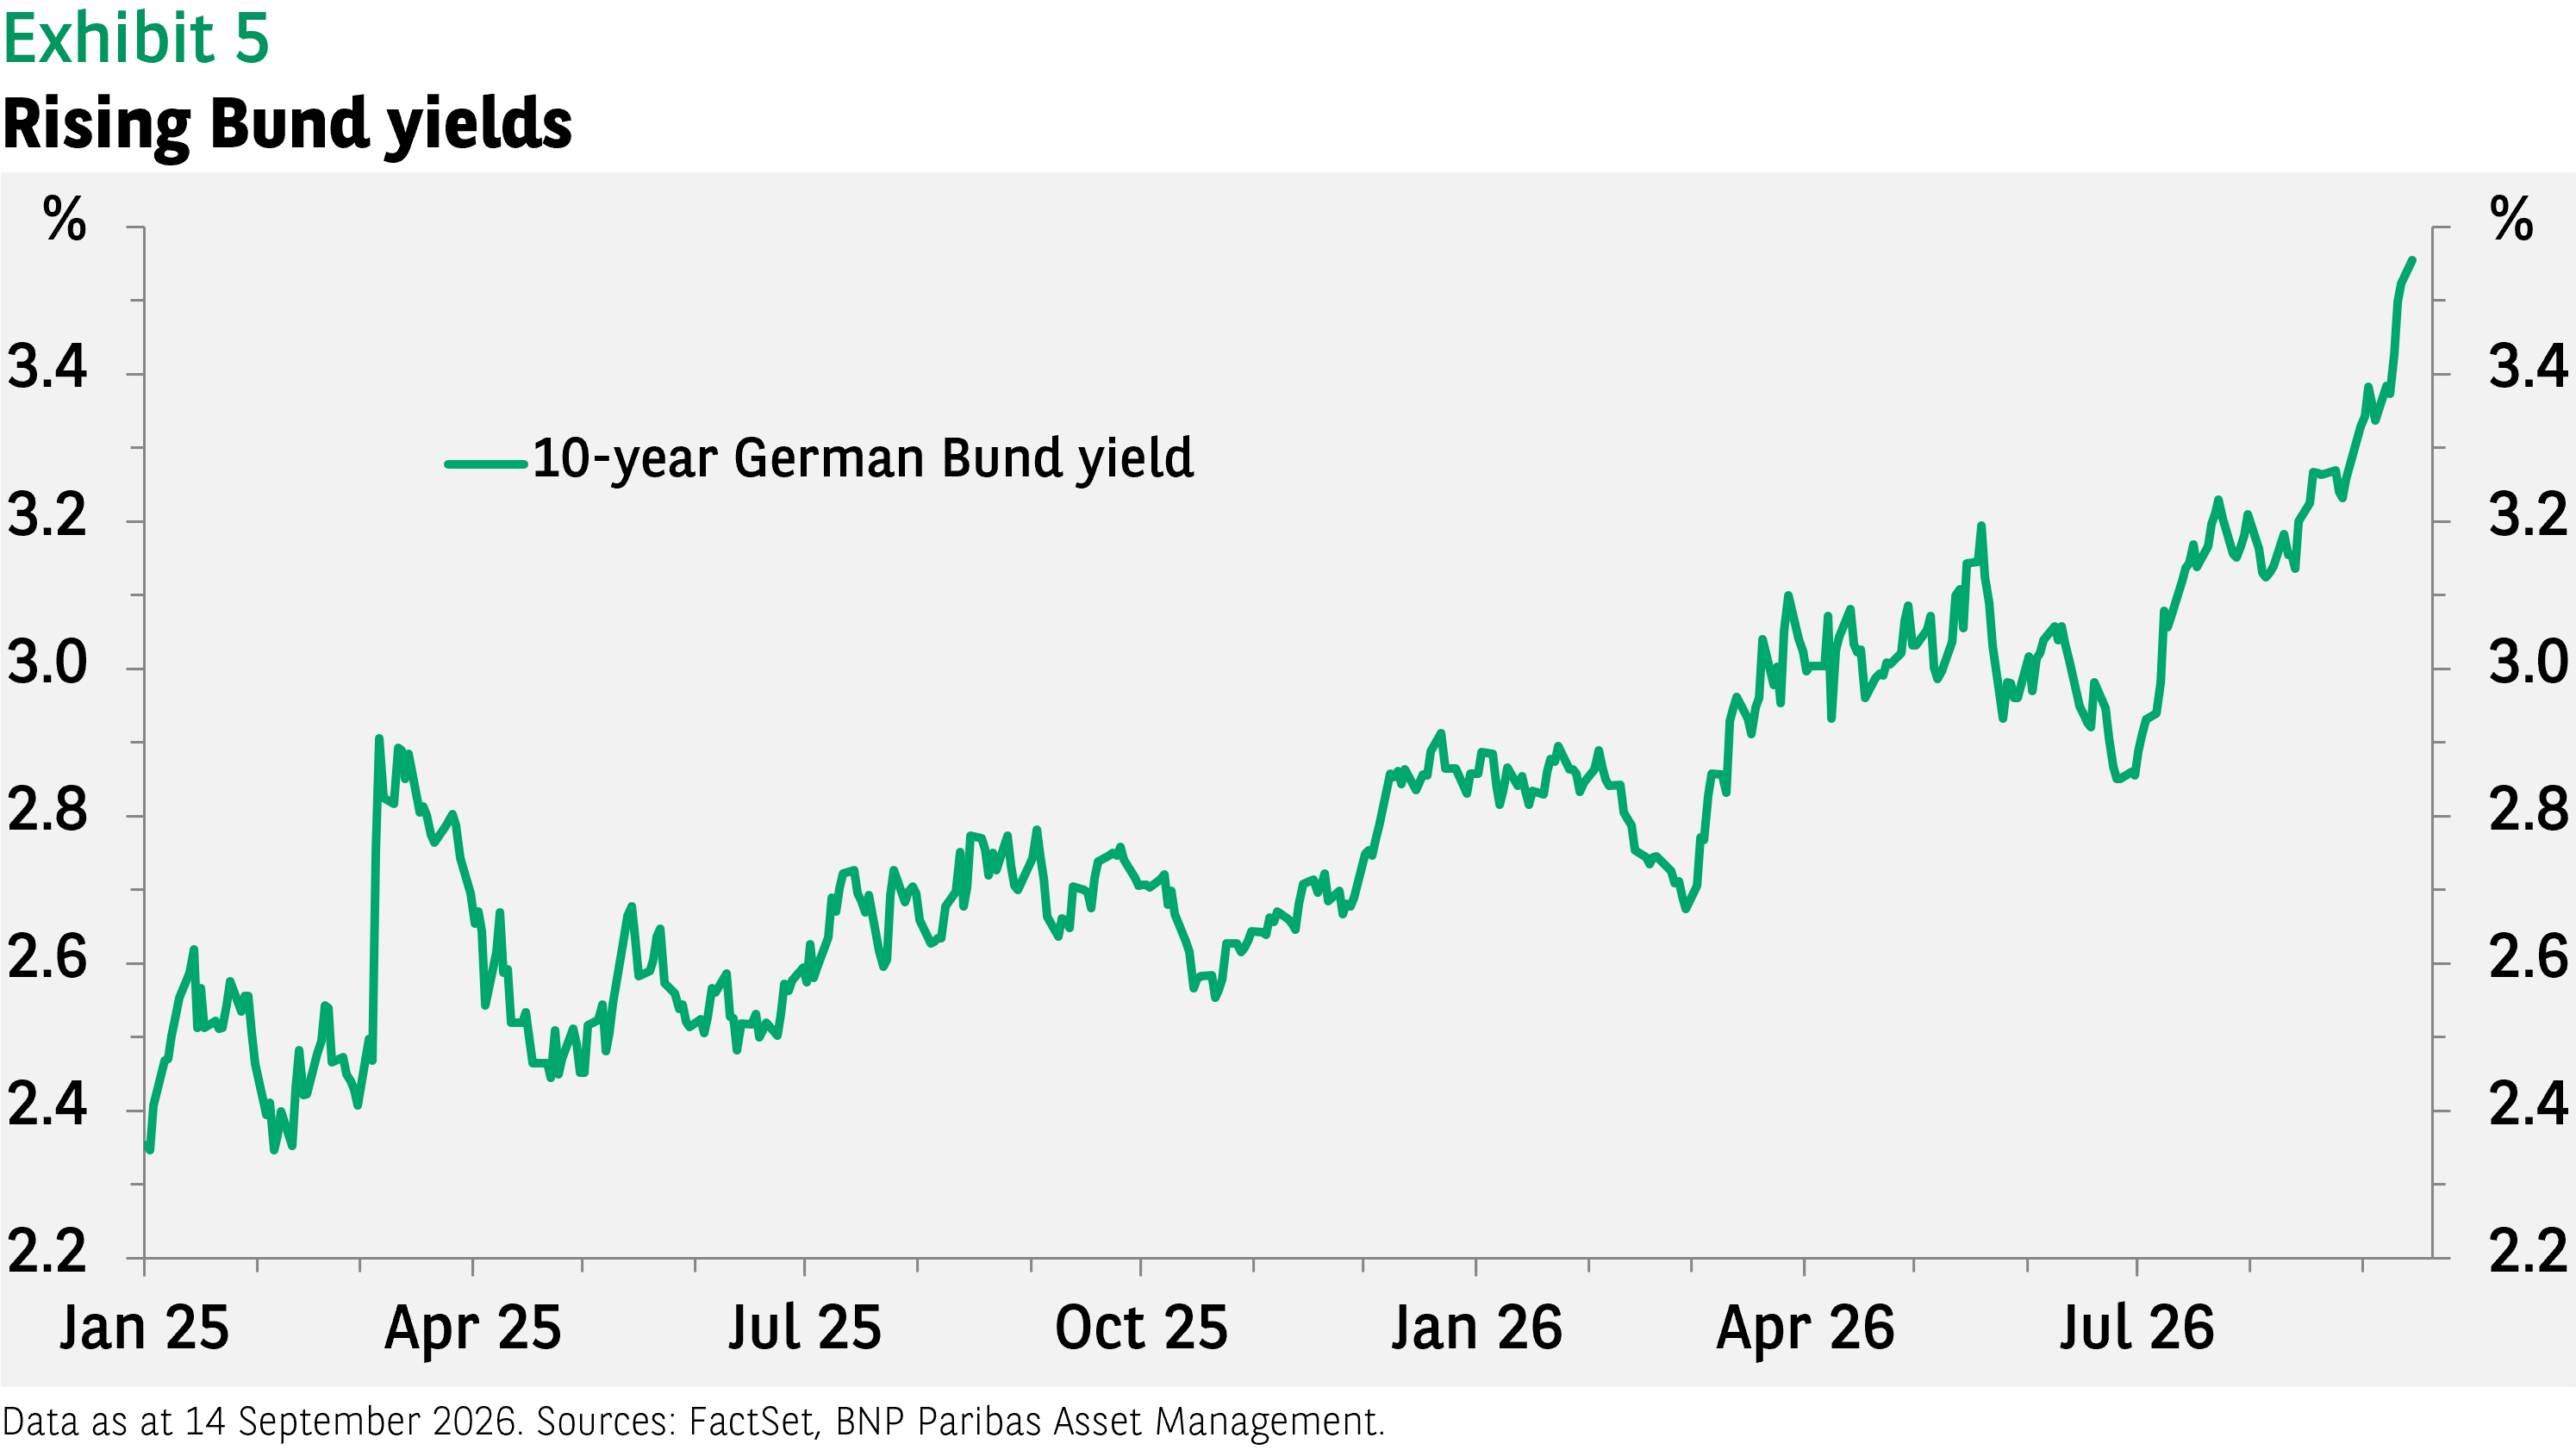
Looking at the past year and a half, 10-year German Bund yields have increased by almost 100bp. But taking a closer look at the chart below, there have been eight phases of rates rallying by more than 25bp.
An agile approach with enough flexibility in terms of duration management can aim to take advantage of this volatility, not only to mitigate losses related to the phases of rates rebound but also to enhance return during these periods.
Risk diversification: Multiple performance drivers within euro fixed income
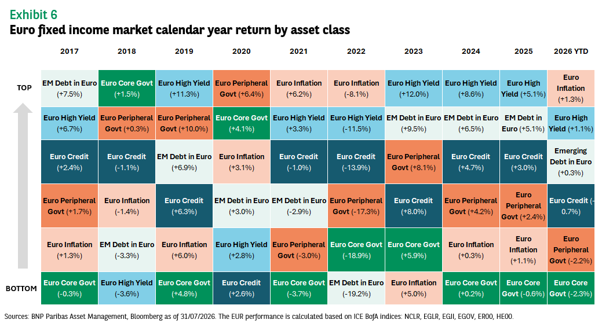
In a period of high uncertainty marked by recurring geopolitical tensions, heavy political agendas, fiscal instability and artificial intelligence expansion, it might be wise to diversify risks.
The euro fixed income market offers access to a wide range of asset classes which, when combined, can potentially help investors navigate different market cycles. Indeed, over the past decade, top performance drivers within the sector have varied from credit to inflation-linked debt, and from emerging market sovereigns to euro core or peripheral sovereigns.
We believe that a flexible allocation across these different drivers has the potential to help investors seize the best opportunities as they arise and subsequently enjoy a better risk-adjusted return.
Holding steady amid instability
Euro fixed income’s appeal may only be rivalled by the current market uncertainty. But as yields keep hitting new highs, we believe the prospects for long term returns improve. Yet, short-term volatility might still unravel investors’ nerves.
Given this backdrop, adopting a flexible and agile approach to duration management while focusing on risk diversification could be the most appropriate way for investors to benefit from (or capture) the euro fixed income opportunity.


Disclaimer
This document is for informational purposes only and does not constitute investment research or financial analysis relating to transactions in financial instruments as per MIF Directive (2014/65/EU), nor does it constitute on the part of BNP PARIBAS ASSET MANAGEMENT Europe or its affiliated companies an offer to buy or sell any investments, products or services, and should not be considered as solicitation or investment, legal or tax advice, a recommendation for an investment strategy or a personalized recommendation to buy or sell securities.
Due to its simplification, this document is partial and opinions, estimates and forecasts herein are subjective and subject to change without notice. There is no guarantee forecasts made will come to pass. Data, figures, declarations, analysis, predictions and other information in this document is provided based on our state of knowledge at the time of creation of this document. Whilst every care is taken, no representation or warranty (including liability towards third parties), express or implied, is made as to the accuracy, reliability or completeness of the information contained herein. Reliance upon information in this material is at the sole discretion of the recipient. This material does not contain sufficient information to support an investment decision.
Issued in the UK by AXA Investment Managers UK Limited, which is authorised and regulated by the Financial Conduct Authority in the UK. Registered in England and Wales, No: 01431068. Registered Office: 22 Bishopsgate, London, EC2N 4BQ.
AXA IM and BNPP AM are progressively merging and streamlining our legal entities to create a unified structure
AXA Investment Managers joined BNP Paribas Group in July 2025. Following the merger of AXA Investment Managers Paris and BNP PARIBAS ASSET MANAGEMENT Europe and their respective holding companies on December 31, 2025, the combined company now operates under the BNP PARIBAS ASSET MANAGEMENT Europe name.