

Take Two: Fed signals further rate increase; US stocks hit record high
What do you need to know?
US interest rates are likely to increase again before the end of 2026, the minutes of the Federal Reserve’s latest meeting showed. All members of the rate-setting committee voted in favour of a 25 basis-point rate hike to 3.75%-4.0% in September, and “most” felt that another hike “would likely be appropriate by year end”. They agreed that inflation risks were “skewed to the upside” – more likely to rise than to fall – though the unemployment rate is expected to remain stable, and economic activity was expanding at a solid pace.
Around the world
Wall Street profits hit $45.9 billion in the first half of this year, up 51% from the same period last year, according to a report from the New York State Comptroller, the state’s financial watchdog. If the pace continues, corporate profits could exceed $90 billion in 2026, it said. The blue-chip S&P 500 index closed above 7,800 for the first time last week while the tech-heavy Nasdaq also hit a fresh record high. Meanwhile government bond yields in the eurozone, UK and US rose early in the week, fuelled by worries over fiscal deficits and inflation, before retreating as oil prices fell.
Figure in focus: $6 trillion
An estimated $6 trillion in artificial intelligence-driven revenue will be needed every year to justify the expected spending on AI infrastructure, according to a new report from consultancy Bain & Company. Annual AI infrastructure spending could reach $1.5 trillion by 2031, it said, and if capital expenditure represents around 25% of industry revenue, “sustaining this level of investment would require an AI market approaching $6 trillion annually.” Productivity gains from existing business and consumer applications are not enough to warrant this scale, Bain said, and new markets must emerge to close the gap.
Chart of the week
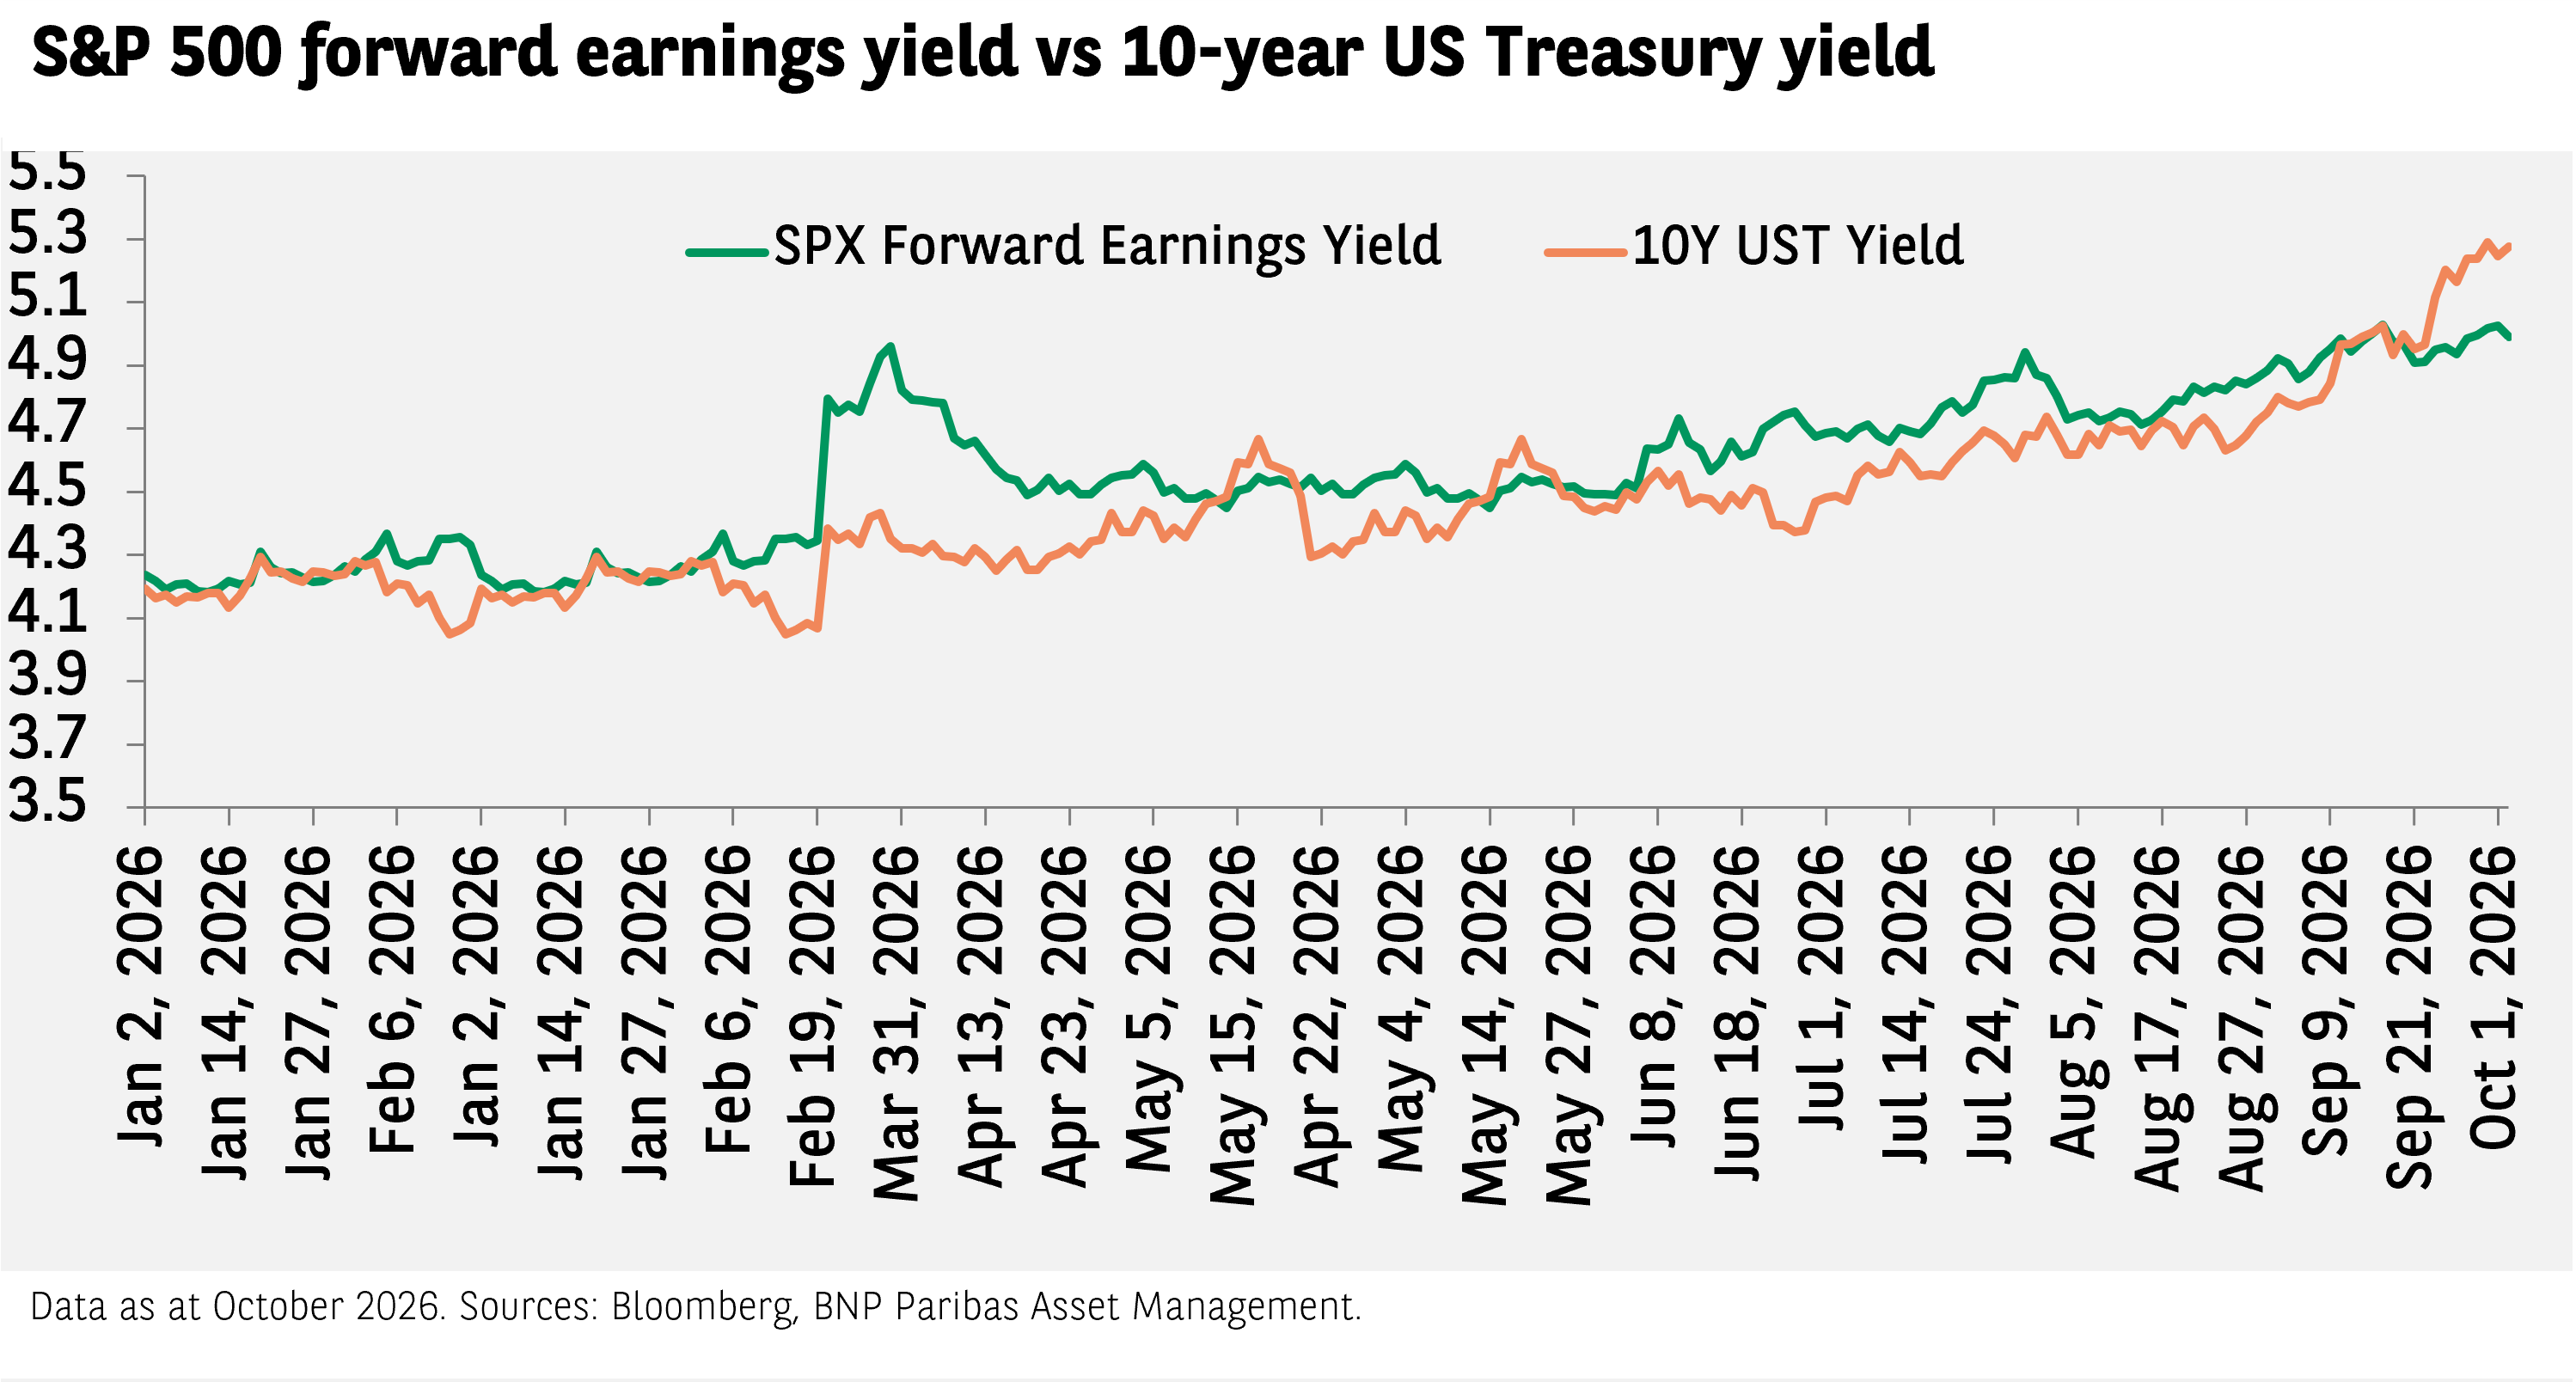
The yield on US 10-year Treasuries now exceeds the expected earnings yield of the S&P 500, suggesting that equities are expensive relative to fixed income. This implies that investors are accepting lower compensation for taking equity risk, likely in anticipation of stronger medium-to-long-term earnings growth. While this reflects robust investor confidence, further increases in bond yields would necessitate either upward earnings revisions or an equity market correction. Conversely, should earnings keep pace with rising yields, the upward trend in equity markets may persist.
Words of wisdom: Pre-COP31
A gathering of ministers and high-level government representatives took place last week to lay the political groundwork for the United Nations climate change conference COP31 in November. The goal of the Pre-COP was to explore solutions for accelerating global climate action, improving access to climate finance and ensuring a fair energy transition. The event, which took place in Fiji and Tuvalu, also highlighted climate policy and solutions for the Pacific island states which are vulnerable to climate change.
What’s coming up?
The Reserve Bank of Australia publishes minutes of its latest monetary policy meeting on Tuesday – it hiked rates by 25bp in September. On Wednesday, China and the US each report their latest inflation data followed by the eurozone on Friday. The International Monetary Fund and World Bank ‘s annual meetings take place in Bangkok from Monday through to Sunday.
Read more insights on [CC2] Viewpoint

Disclaimer
This document is for informational purposes only and does not constitute investment research or financial analysis relating to transactions in financial instruments as per MIF Directive (2014/65/EU), nor does it constitute on the part of BNP PARIBAS ASSET MANAGEMENT Europe or its affiliated companies an offer to buy or sell any investments, products or services, and should not be considered as solicitation or investment, legal or tax advice, a recommendation for an investment strategy or a personalized recommendation to buy or sell securities.
Due to its simplification, this document is partial and opinions, estimates and forecasts herein are subjective and subject to change without notice. There is no guarantee forecasts made will come to pass. Data, figures, declarations, analysis, predictions and other information in this document is provided based on our state of knowledge at the time of creation of this document. Whilst every care is taken, no representation or warranty (including liability towards third parties), express or implied, is made as to the accuracy, reliability or completeness of the information contained herein. Reliance upon information in this material is at the sole discretion of the recipient. This material does not contain sufficient information to support an investment decision.
Issued in the UK by AXA Investment Managers UK Limited, which is authorised and regulated by the Financial Conduct Authority in the UK. Registered in England and Wales, No: 01431068. Registered Office: 22 Bishopsgate, London, EC2N 4BQ.
AXA IM and BNPP AM are progressively merging and streamlining our legal entities to create a unified structure
AXA Investment Managers joined BNP Paribas Group in July 2025. Following the merger of AXA Investment Managers Paris and BNP PARIBAS ASSET MANAGEMENT Europe and their respective holding companies on December 31, 2025, the combined company now operates under the BNP PARIBAS ASSET MANAGEMENT Europe name.