
Take Two: IMF lifts global growth forecast; US inflation rises
What do you need to know?
The International Monetary Fund raised its 2026 global growth forecast to 3.1% from the 3.0% it projected in July but kept its 2027 forecast unchanged at 3.4%. Meanwhile it expects global inflation to increase to 4.7% this year from 4.1% in 2025, before easing back to 4.1% in 2027. The global economy has remained resilient thanks to the re-routing of energy supplies, mitigating the impact of geopolitical conflicts, as well as an artificial intelligence investment boom, the IMF said. However, it warned that countries need to rebuild financial reserves and shore up capacity to withstand future shocks.
Around the world
US annual inflation rose more than expected in September, increasing to 3.7% from 3.4% in August. The rise was primarily driven by higher gasoline and energy prices. Core inflation, which excludes more volatile food and energy costs, rose to 2.6% in September, from 2.4% in August. The data raised expectations that the Federal Reserve could hike interest rates further, prompting stock markets to fall before later recovering. The S&P 500 was flat in the week to Thursday’s close while the tech-heavy Nasdaq was down 2%. Europe’s STOXX 600 gained 2%*. Elsewhere, eurozone annual inflation was confirmed at 3.8% in September, up from 3.2% in August.
*In US dollar terms. Source: FactSet, data as of 15 October 2026
Figure in focus: Four years
The current bull market – a period when share prices are rising – marked its four-year anniversary last week. The rally began in October 2022 as stock markets rebounded from their lows, which were brought on by central banks aggressively hiking interest rates following the post-pandemic inflation spike. The MSCI World and S&P 500 have each climbed nearly 120% since then, according to reports. The strong performance has been driven by corporate earnings growth and optimism over artificial intelligence, though some investors have questioned how long the upward trend can continue. A bull market is considered to have ended when the index falls at least 20% from its peak.
Chart of the week
US business activity’s fastest rise in more than five years is helping investors remain optimistic about the outlook for stock markets. The S&P Global US Purchasing Managers’ Index – which measures the private sector’s economic health across manufacturing and services industries – rose to 58.4 in September from 56 in August. A reading above 50 marks expansion. Growth accelerated across both manufacturing and services, indicating broad-based strength in the US economy. AI investment and defence spending boosted the manufacturing sector, while inventory stockpiling resulted in higher orders and output. This positive backdrop continues to support equities and other risk-based assets, despite expectations of higher interest rates.
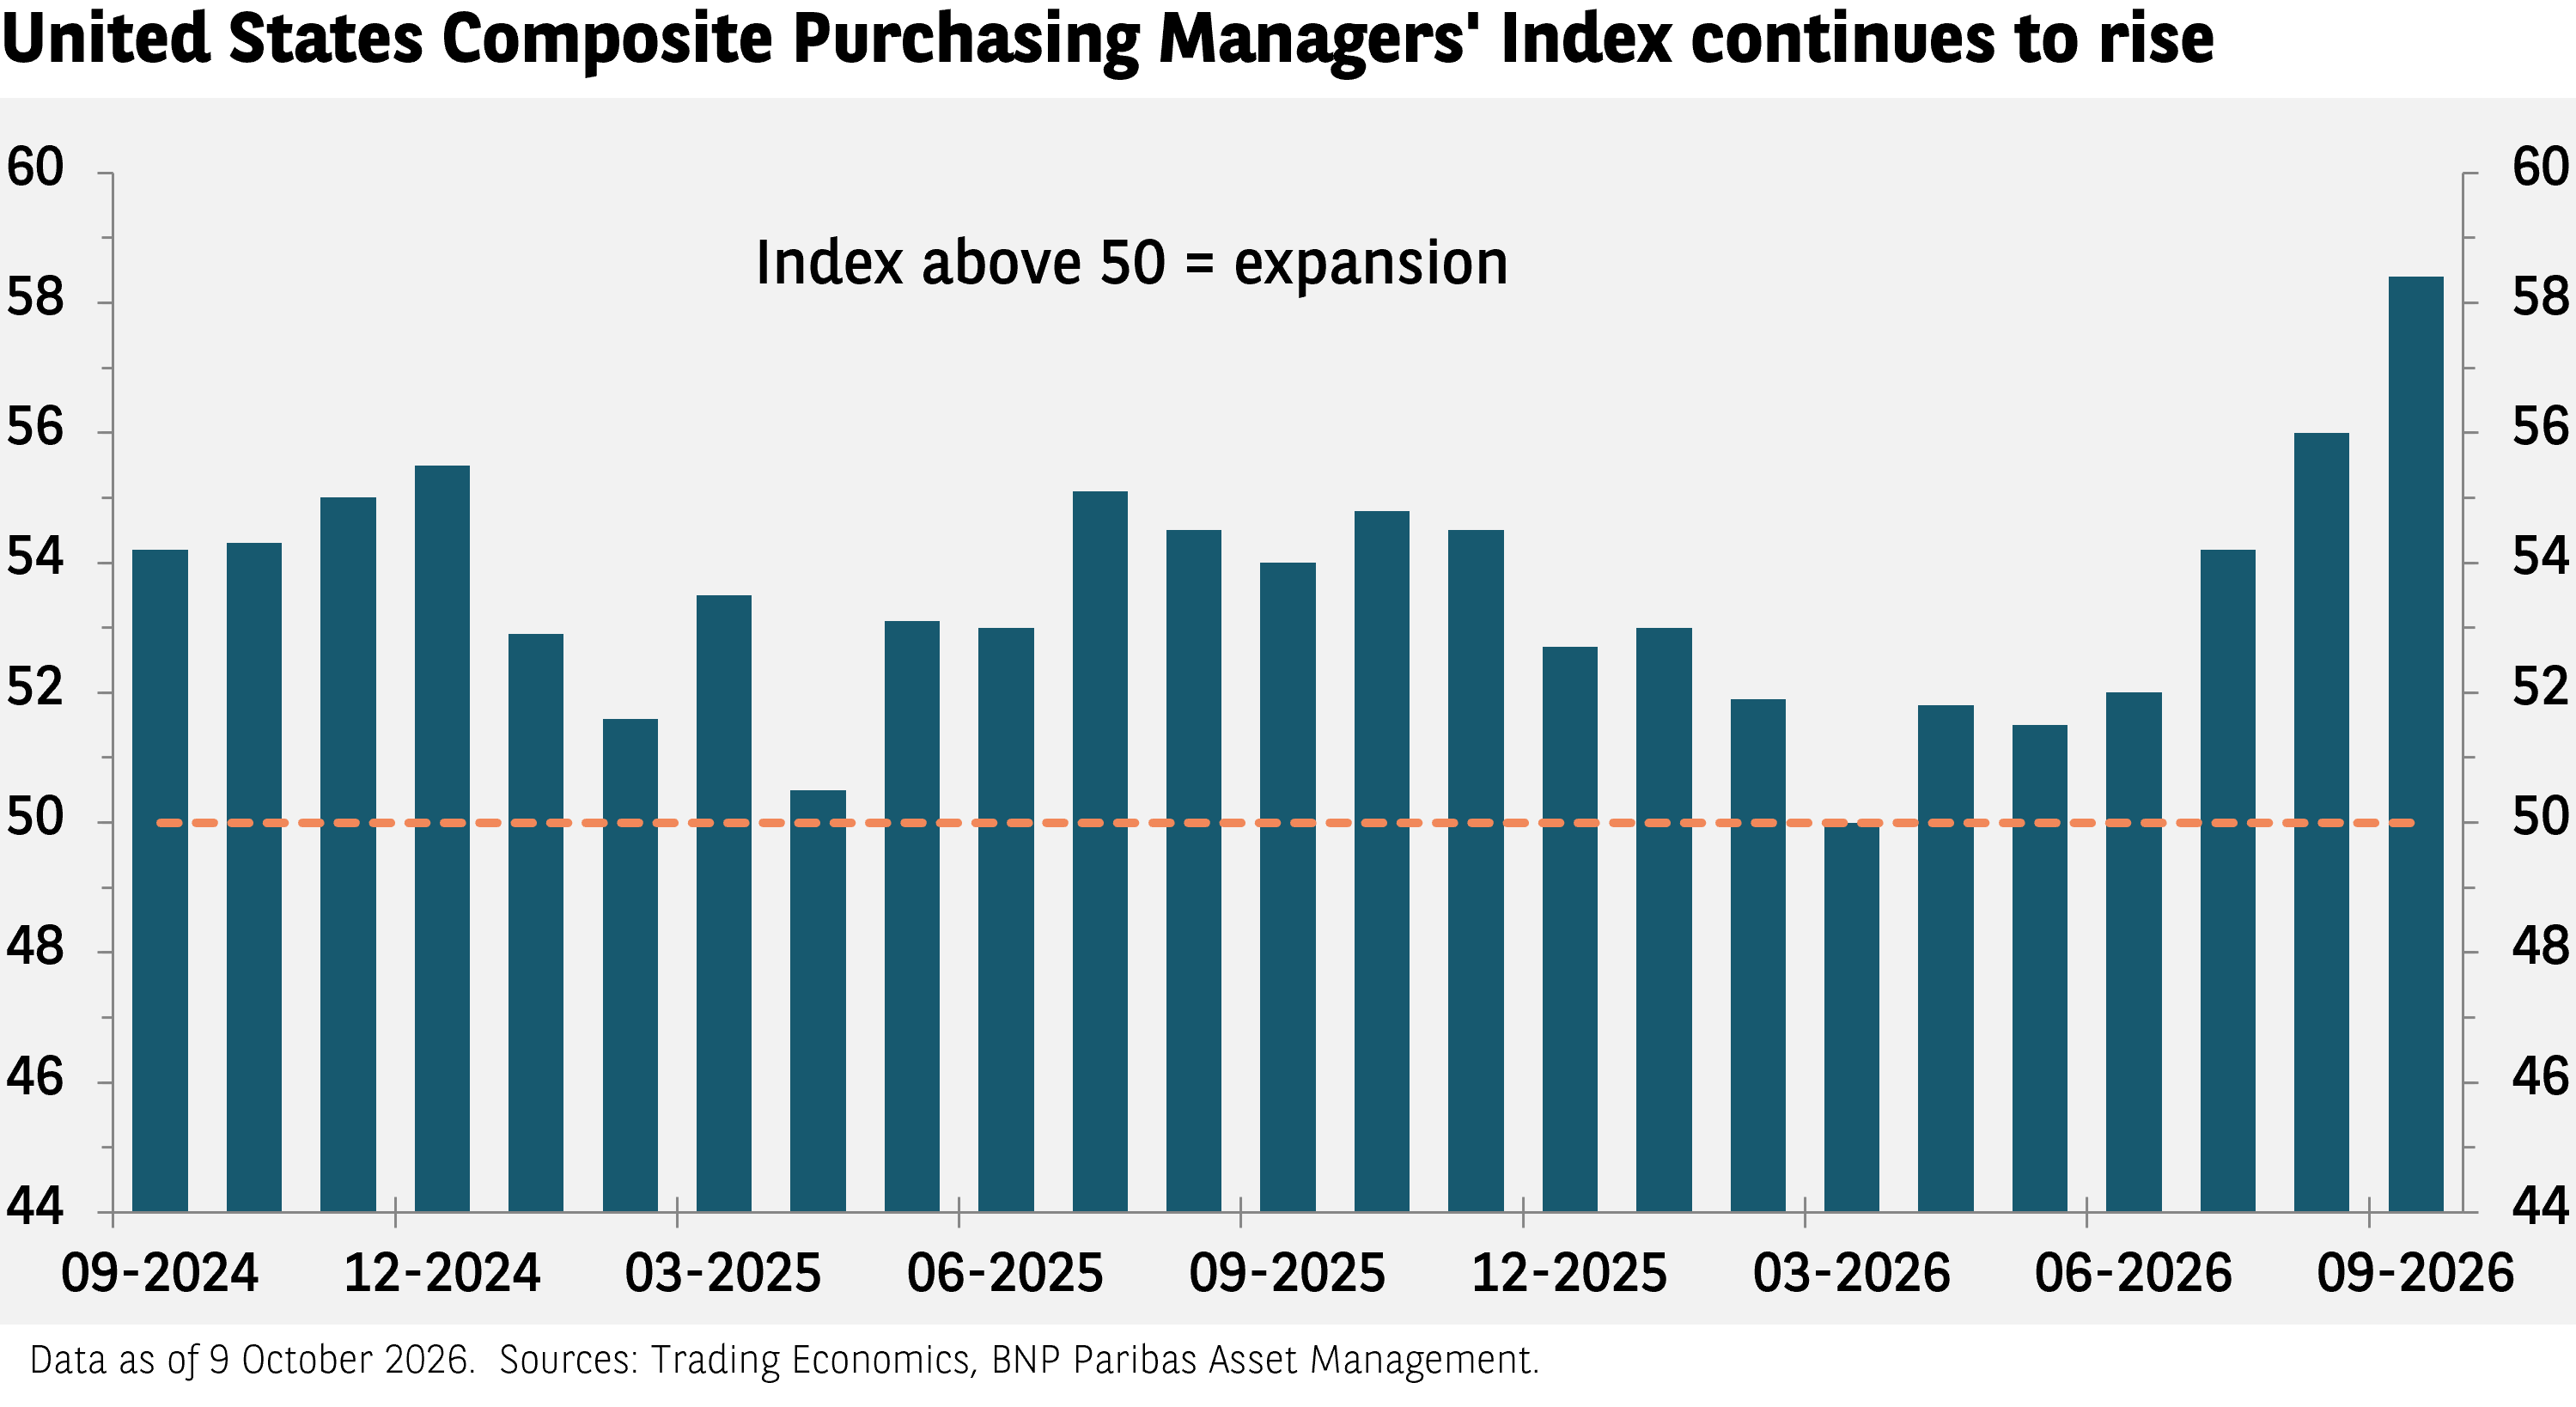
Words of wisdom: Microeconomics
How individual consumers or businesses make economic decisions, such as what to purchase or setting prices for their products. Two US professors won the Nobel Prize in Economic Sciences last week for their work on microeconomics. Robert E. Hall and Michael Woodford developed new models showing how the combined actions of individual households and businesses affect the economy. Their models have helped central banks deal with shocks like energy crises, by using monetary policy to stabilise economies.
What’s coming up?
On Monday, China publishes its third quarter GDP growth rate and Canada reports September inflation data. The UK follows with its own inflation figures on Wednesday. On Thursday, the eurozone publishes its latest consumer confidence survey. Friday sees Japan report inflation data while a series of Purchasing Managers’ Indices are released, covering business activity in the eurozone, US, UK and Japan.


Disclaimer
This document is for informational purposes only and does not constitute investment research or financial analysis relating to transactions in financial instruments as per MIF Directive (2014/65/EU), nor does it constitute on the part of BNP PARIBAS ASSET MANAGEMENT Europe or its affiliated companies an offer to buy or sell any investments, products or services, and should not be considered as solicitation or investment, legal or tax advice, a recommendation for an investment strategy or a personalized recommendation to buy or sell securities.
Due to its simplification, this document is partial and opinions, estimates and forecasts herein are subjective and subject to change without notice. There is no guarantee forecasts made will come to pass. Data, figures, declarations, analysis, predictions and other information in this document is provided based on our state of knowledge at the time of creation of this document. Whilst every care is taken, no representation or warranty (including liability towards third parties), express or implied, is made as to the accuracy, reliability or completeness of the information contained herein. Reliance upon information in this material is at the sole discretion of the recipient. This material does not contain sufficient information to support an investment decision.
Issued in the UK by AXA Investment Managers UK Limited, which is authorised and regulated by the Financial Conduct Authority in the UK. Registered in England and Wales, No: 01431068. Registered Office: 22 Bishopsgate, London, EC2N 4BQ.
AXA IM and BNPP AM are progressively merging and streamlining our legal entities to create a unified structure
AXA Investment Managers joined BNP Paribas Group in July 2025. Following the merger of AXA Investment Managers Paris and BNP PARIBAS ASSET MANAGEMENT Europe and their respective holding companies on December 31, 2025, the combined company now operates under the BNP PARIBAS ASSET MANAGEMENT Europe name.